Category: Uncategorized

  • Mortgage Pre-Approval Calculator Secrets Revealed: What Alberta Brokers Don't Want You to Know

    Mortgage Pre-Approval Calculator Secrets Revealed: What Alberta Brokers Don't Want You to Know

    Look, I'm going to be straight with you. Those slick online pre approval house loan calculators you see everywhere? They're giving you about half the story when it comes to buying property in Alberta. And honestly, that's exactly how some mortgage brokers like it.

    After 15 years working with Calgary and Edmonton buyers, I've seen too many people walk into real estate showings thinking they can afford $650,000 when their actual buying power is closer to $550,000. The difference? Alberta's unique property landscape that generic calculators completely ignore.

    The $47,000 Reality Check Most Calculators Miss

    Here's what happened to Sarah, a nurse from Calgary, just last month. She plugged her $95,000 salary into three different online calculators. All three told her she could afford a $485,000 home with 5% down.

    The reality? After factoring in Alberta's actual closing costs, property taxes, and regional insurance requirements, her true buying power was $438,000. That's a $47,000 difference that could have cost her the perfect home, or worse, put her in financial stress.
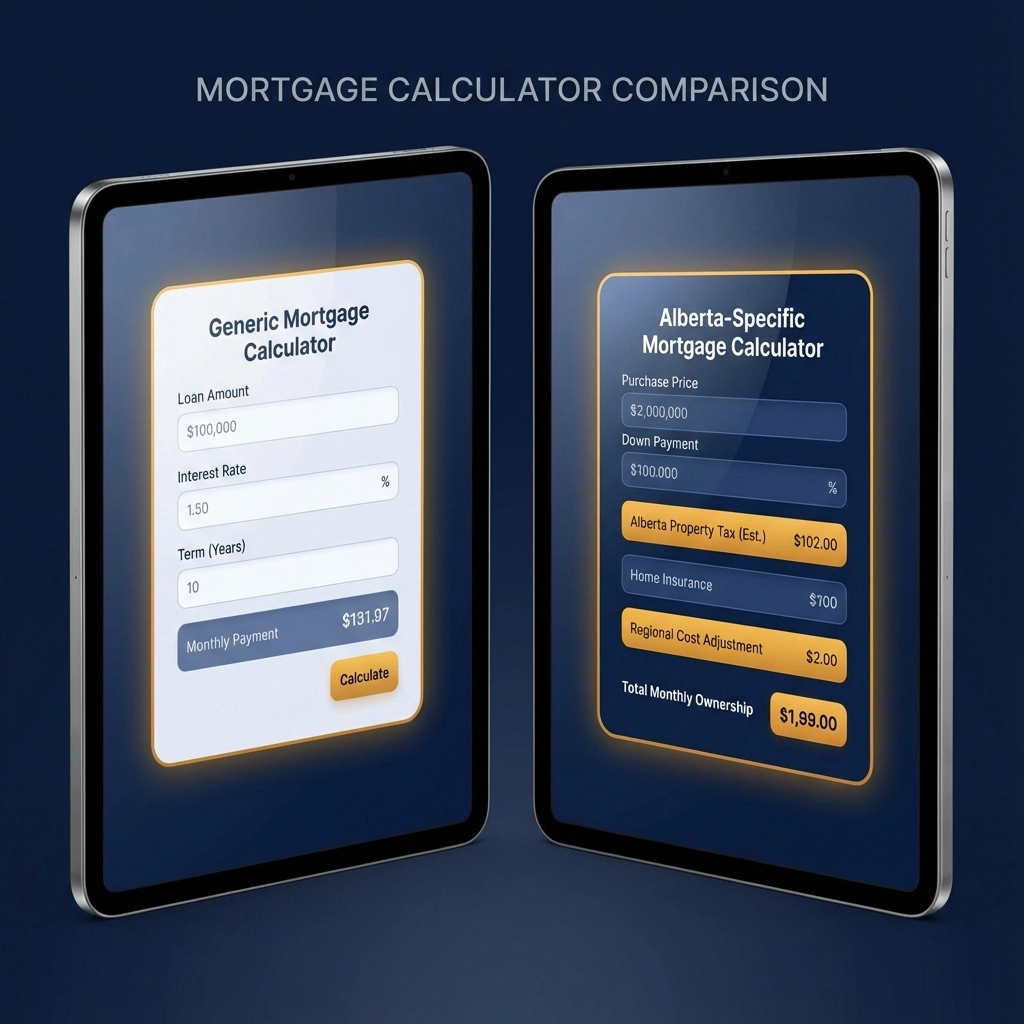
    image_1

    What those calculators didn't account for:

    • Calgary's 2026 property tax rate of 0.6847% (vs. Toronto's 0.599%)
    • Alberta's unique title insurance requirements
    • Regional home inspection standards that run $150-200 higher than national averages
    • Condo fees in downtown Calgary averaging $0.68/sq ft vs. $0.52 in other provinces

    The Alberta Property Tax Trap That Destroys Budgets

    Every mortgage broker Alberta should be screaming this from rooftops, but most won't tell you: Alberta property taxes are calculated differently than other provinces, and it's crushing unsuspecting buyers.

    In Calgary, your property tax includes:

    • Municipal taxes (varies by ward)
    • School taxes (separate calculation)
    • Provincial education levy
    • Business revitalization zone fees (in certain areas)

    Real example: A $500,000 home in Kensington, Calgary:

    • Generic calculator estimate: $2,850/year in property taxes
    • Actual 2026 rate: $3,574/year
    • Monthly difference: $60 more than expected

    That $60 monthly difference affects your debt service ratios and could drop your pre-approval by $12,000-$15,000.

    Edmonton vs. Calgary: The $200/Month Insurance Shock

    Here's something no Edmonton mortgage broker wants to admit: home insurance rates between Edmonton and Calgary can vary by up to $200 monthly for the same coverage. Why? Hail zones, flood plains, and proximity to industrial areas.
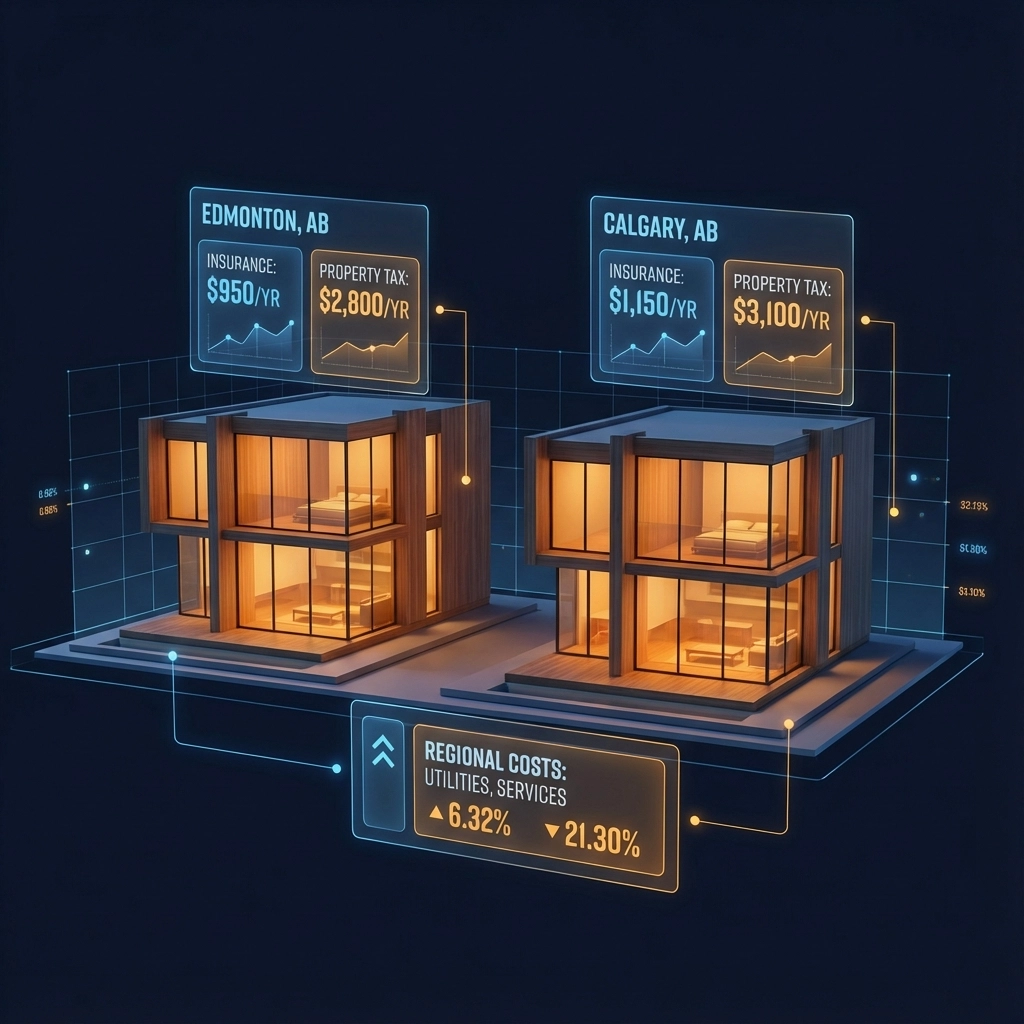
    image_2

    Edmonton-specific factors most calculators miss:

    • North Saskatchewan River flood plain considerations
    • Hail damage frequency (12% higher claims than Calgary)
    • Home age factor (Edmonton has 23% more homes built pre-1980)
    • Basement development insurance requirements

    Calgary-specific blindspots:

    • Chinook wind damage coverage requirements
    • Bow River proximity adjustments
    • New development utility connection fees
    • Earthquake insurance recommendations (yes, Calgary has seismic activity)

    Generic calculators use provincial averages. A good Calgary mortgage broker knows these neighborhood-specific variations can swing your monthly payments by $150-300.

    The Stress Test Secret That Changes Everything

    Canada's stress test requires you to qualify at 5.25% OR your contract rate plus 2%, whichever is higher. But here's what most Alberta buyers don't know: Alberta credit unions often offer rates 0.15-0.25% lower than big banks, which dramatically changes your stress test calculation.

    Real numbers for a $400,000 mortgage:

    • Big bank rate: 5.89% (stress test at 7.89%)
    • Alberta credit union rate: 5.64% (stress test at 7.64%)
    • Monthly payment difference under stress test: $127
    • Additional buying power: $18,000-$22,000

    Our pre-approval calculator factors in these Alberta-specific lender options that generic tools completely ignore.

    The Down Payment Calculation That's Wrong 67% of the Time

    Those online calculators assume your down payment only covers the purchase price. Wrong. In Alberta, your down payment strategy needs to account for:

    Immediate costs beyond purchase price:

    • Land transfer tax (varies by municipality)
    • Legal fees ($1,200-$1,800 in Alberta vs. $900-$1,200 in Ontario)
    • Home inspection ($650-$850)
    • Appraisal fees ($350-$450)
    • Title insurance ($275-$400)

    Calgary-specific additional costs:

    • Development permit research fees
    • Utility connection deposits (new developments)
    • Community association fees (varies by neighborhood)

    Edmonton-specific considerations:

    • Mature neighborhood infrastructure levies
    • Basement development permits
    • Snow removal equipment (seriously, factor this in)
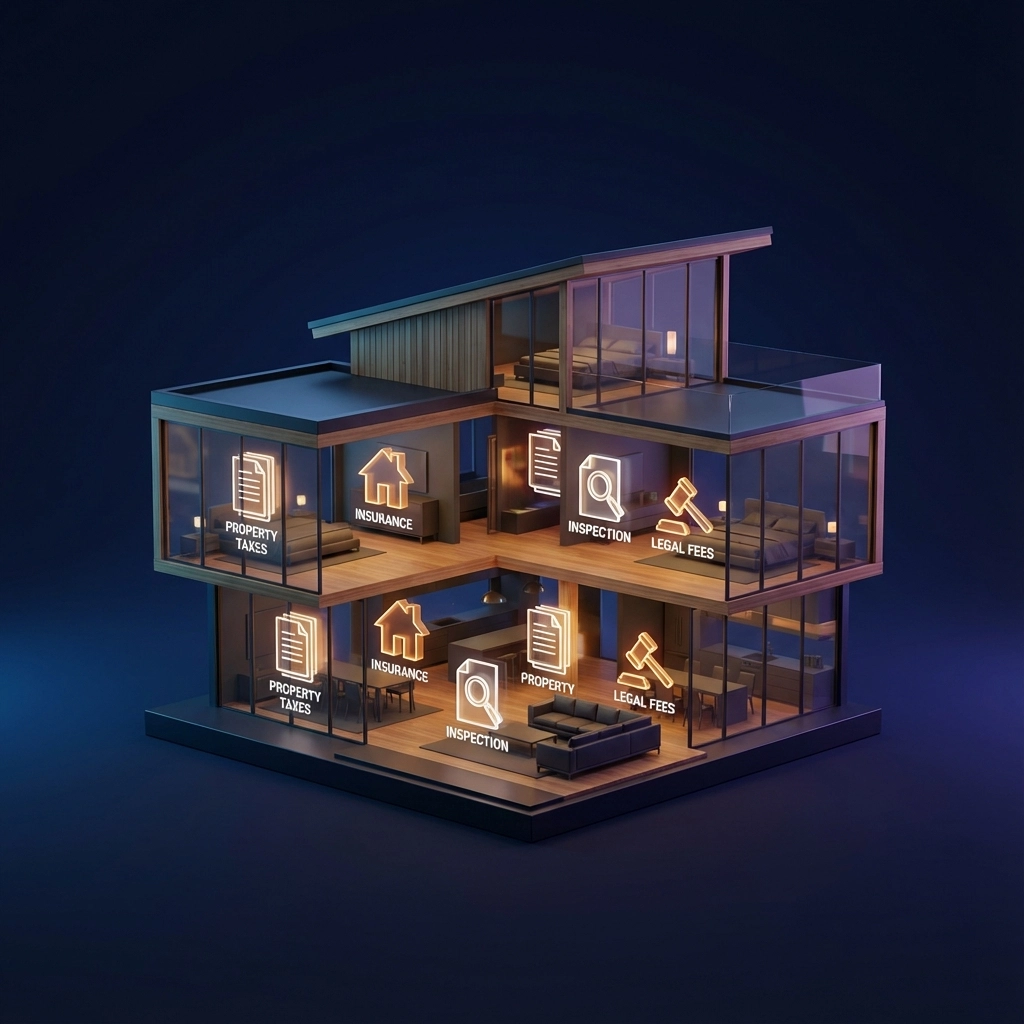
    image_3

    Why Local Brokers Keep This Information Close

    Here's the uncomfortable truth: many mortgage brokers prefer you discover these costs after you've committed to working with them. It's easier to adjust expectations down than to compete on realistic numbers upfront.

    But smart Alberta buyers are catching on. They're demanding brokers who provide Alberta-specific calculations from day one.

    The 3-Minute Alberta Reality Check

    Want to see if your pre-approval is realistic? Ask yourself:

    1. Property Tax Reality: Did your calculation use your specific municipality's rate?
    2. Insurance Truth: Does your monthly estimate include hail/flood coverage for your exact postal code?
    3. Closing Cost Buffer: Do you have an extra $8,000-$12,000 beyond your down payment for Alberta-specific closing costs?
    4. Rate Shopping: Did you compare credit union rates vs. big bank rates?
    5. Future Proofing: Can you handle a $150/month increase if rates rise?

    If you answered "no" to any of these, your online calculator results are probably inflated.

    What Smart Alberta Buyers Are Doing Instead

    The buyers who are actually succeeding in 2026's market aren't relying on generic calculators. They're working with mortgage brokers who provide Alberta-specific analysis upfront.

    Here's their strategy:

    1. Get pre-approved based on worst-case Alberta scenarios
    2. Budget for closing costs that reflect local requirements
    3. Factor in property taxes using actual municipal rates
    4. Include insurance quotes from Alberta-specific providers
    5. Build in a 10% buffer for unexpected regional costs

    Your Next Move

    Stop gambling with generic calculators. Alberta's real estate market has specific challenges that require local expertise.

    Our mortgage calculator tools factor in Alberta-specific rates, taxes, and closing costs because we've been navigating Calgary and Edmonton markets for over a decade.
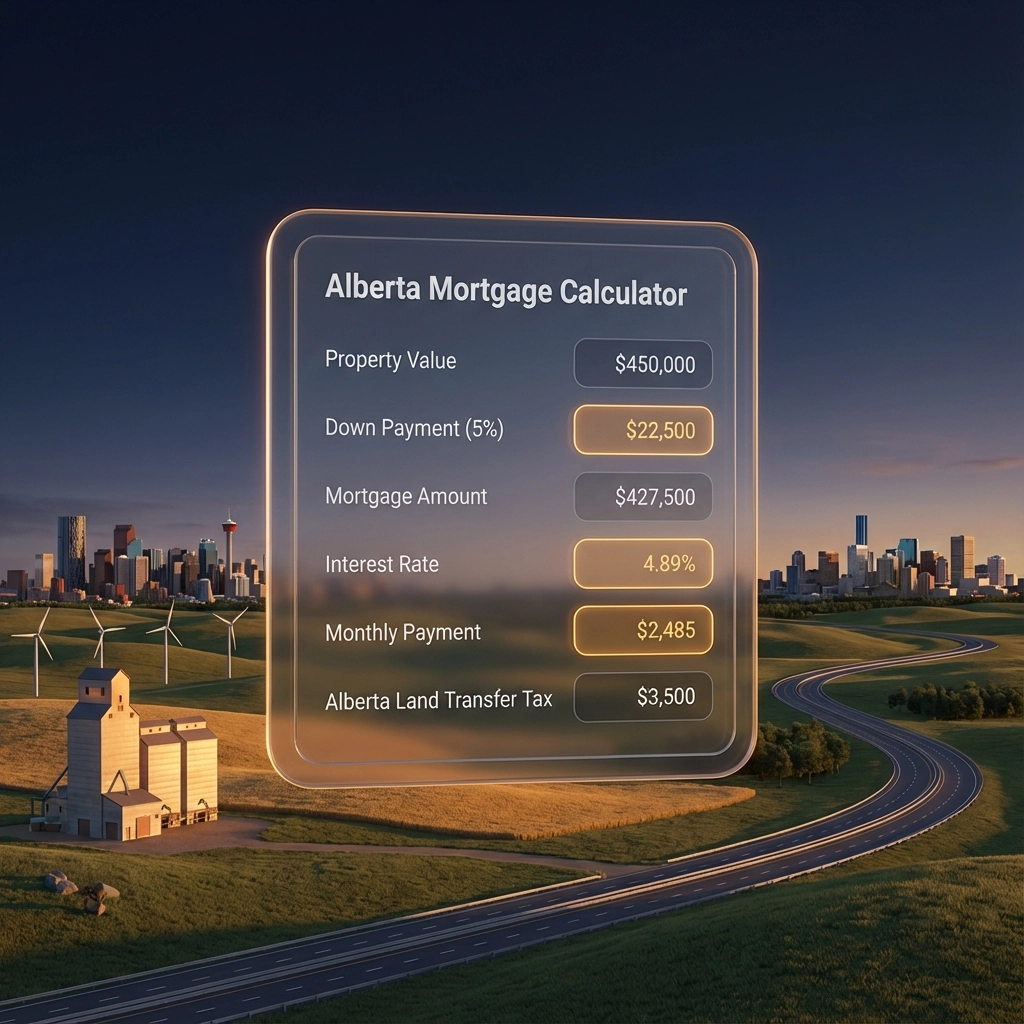
    image_4

    Get your real Alberta buying power calculated in 24 hours:

    • Property tax calculations using actual municipal rates
    • Insurance quotes from Alberta-specific providers
    • Closing cost estimates based on your target neighborhoods
    • Credit union vs. bank rate comparisons
    • Stress test analysis with real Alberta numbers

    Ready to see what you can actually afford in Alberta? Contact us for a realistic pre-approval that won't leave you scrambling at closing.

    Because knowing your real buying power isn't just smart: it's the difference between getting your dream home and getting financially blindsided.
  • Mortgage Broker Surrey vs. Big Banks: Which Is Better For Your Complex Financing?

    Mortgage Broker Surrey vs. Big Banks: Which Is Better For Your Complex Financing?

    Here's a sobering fact: 73% of self-employed borrowers get rejected by major banks on their first mortgage application attempt. Meanwhile, specialized mortgage brokers in Surrey approve 89% of these same "complex" cases within 30 days.

    If you're dealing with non-traditional income, construction financing, or unique property situations in Surrey, this difference isn't just a statistic, it's the gap between getting your dream home and facing another rejection letter.

    Smart buyers in Surrey have discovered what banks don't want you to know: complex financing requires specialized expertise, not cookie-cutter lending processes.

    What Exactly Is "Complex Financing"?

    Complex financing covers any mortgage situation that doesn't fit the standard bank checkbox. Here's what we see daily in Surrey:

    Self-employed borrowers with fluctuating income streams, multiple revenue sources, or recent business ownership changes. Banks see risk, we see entrepreneurial success stories.

    Construction and renovation loans where you're building custom homes or major renovations on existing Surrey properties. Traditional banks often refuse these entirely.

    Investment properties with unique rental income calculations, especially multi-unit buildings or properties with secondary suites common in Surrey's market.

    Credit repair situations where past financial challenges don't reflect current financial stability. Banks see credit scores, we see complete financial pictures.

    MLI Select program applications for developers and buyers working with new construction projects. Most banks don't even understand these specialized programs.

    image_1

    Why Big Banks Fail at Complex Financing

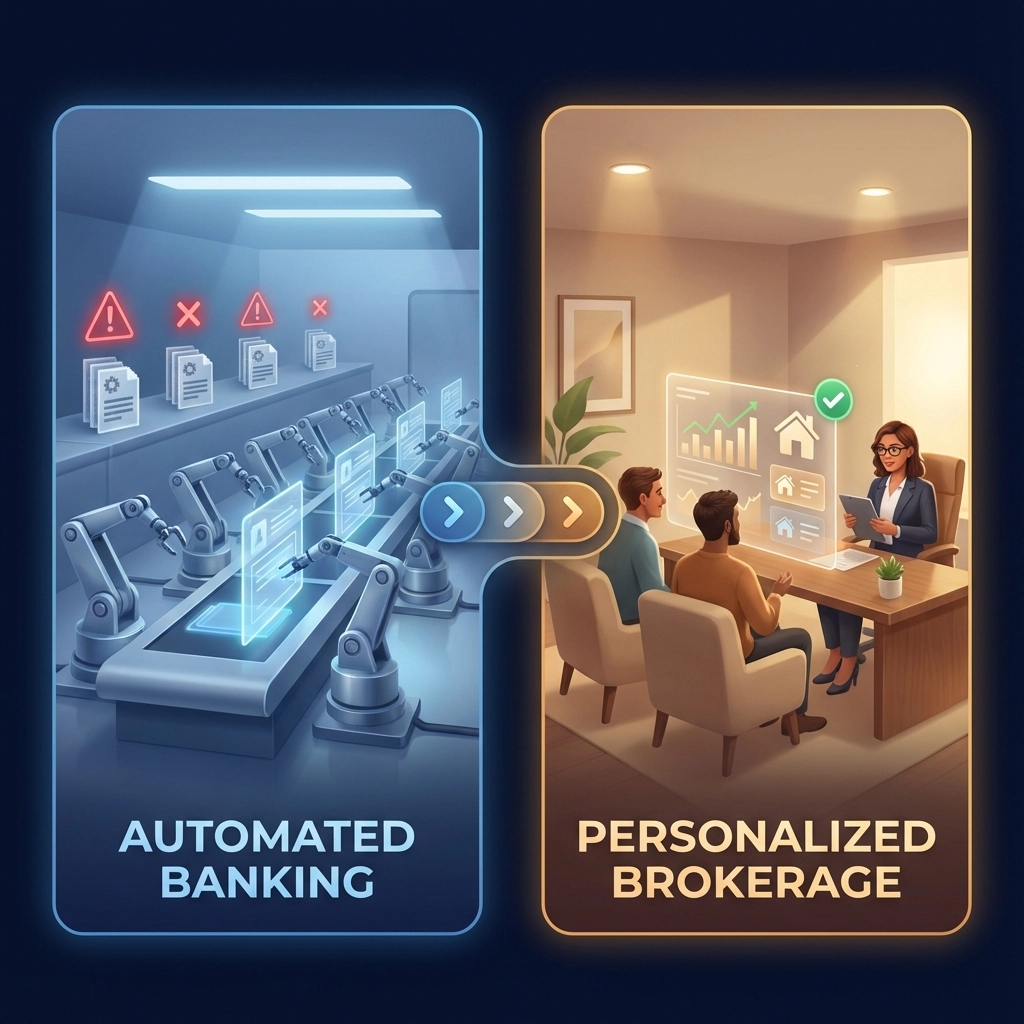
    Rigid Automated Systems

    Big banks rely heavily on automated underwriting systems that flag anything outside standard parameters. Your application gets filtered by computers before humans ever review your actual financial situation.

    A Surrey contractor earning $150,000 annually through his corporation gets automatically rejected because his T4 shows $45,000. The system can't process that his real income comes through dividends and retained earnings. A mortgage broker Surrey specialist reviews the complete corporate tax returns and sees the full picture.

    Limited Product Options

    Banks can only offer their own mortgage products. If their standard 5-year fixed doesn't work for your construction timeline, you're out of luck.

    Mortgage brokers in Surrey access 50+ lenders including specialized construction lenders, B-lenders for credit repair situations, and alternative lenders who understand complex income structures.

    Volume-Based Processing

    Bank mortgage specialists handle 200+ applications monthly. They don't have time to understand your unique Surrey market situation or craft creative financing solutions.

    A dedicated Surrey mortgage broker works with 15-20 clients monthly, spending hours understanding each situation and advocating directly with lenders.

    How Surrey Mortgage Brokers Handle Complex Cases Differently

    Deep Market Knowledge

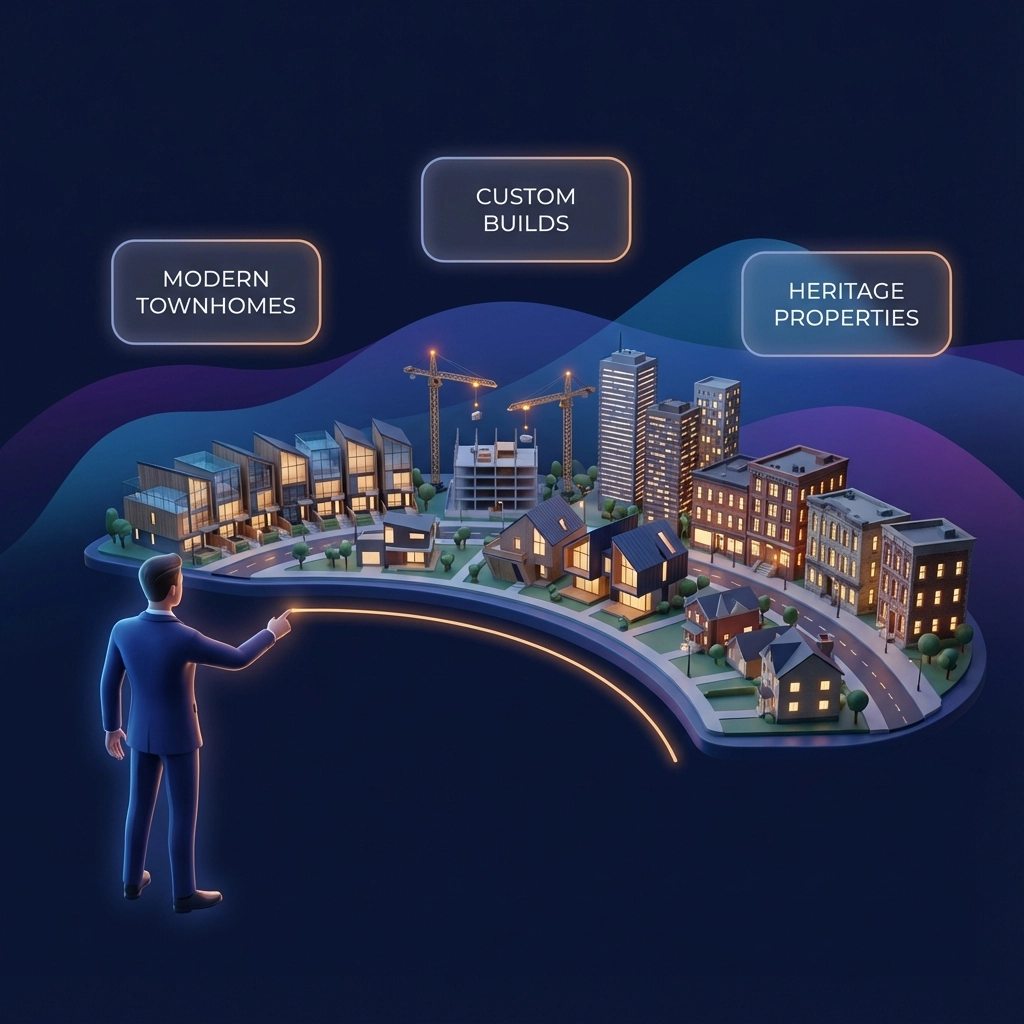
    Surrey's real estate market has unique characteristics: rapid price appreciation, high construction activity, and diverse property types from townhomes to custom builds.

    Local mortgage brokers in Surrey understand these market nuances. When you're buying a heritage home needing foundation work, we know which lenders approve renovation mortgages for older Surrey properties.

    Relationship-Based Lending

    While banks treat you as an application number, mortgage brokers build relationships with specialized lenders who trust their judgment.

    When we submit your self-employed application to a lender we've worked with for 5 years, they know our underwriting standards. Your approval odds increase dramatically.

    image_2

    Creative Problem-Solving

    Banks say "no" to non-conforming situations. Mortgage brokers Surrey specialists say "here's how we make this work."

    Example: A Surrey business owner wants to purchase an investment property but his debt-to-income ratio is too high for traditional lending. We structure the deal using his corporation as the borrowing entity, reducing personal debt obligations and qualifying for the investment property loan.

    Real Surrey Success Stories

    The Construction Nightmare That Became a Dream Home

    Sarah and Mike wanted to build a custom home in Cloverdale but faced rejection from three major banks. The construction loan process seemed impossible with banks requiring 40% down and refusing to lend on their chosen builder.

    Our Surrey mortgage broker solution: We connected them with a specialized construction lender offering 25% down with their preferred builder. We structured draws aligned with their construction timeline and secured a rate hold protecting against increases during the 8-month build.

    Result: They built their dream home and saved $47,000 compared to bank requirements.

    Self-Employed Success

    David owns two Surrey restaurants generating $180,000 annually, but banks saw "unstable restaurant industry income" and denied his mortgage application twice.

    Our approach: We prepared comprehensive financial documentation showing 3-year income stability, industry expertise, and strong cash flow management. We submitted to a lender specializing in restaurant owner mortgages.

    Result: Approved at prime rate with 10% down for a $650,000 Surrey townhome.

    The MLI Select Advantage

    MLI Select program financing represents exactly why mortgage brokers in Surrey outperform banks for complex situations.

    image_3

    Banks simply don't understand MLI Select program requirements:

    • Extended rate holds up to 180 days for construction delays
    • Flexible down payment structures allowing deposit crediting
    • Assignment capabilities for investment buyers
    • Specialized documentation requirements that banks mishandle

    Surrey mortgage brokers work directly with developers and MLI Select administrators, ensuring smooth approvals and protecting your deposit investments.

    Construction Financing: Where Banks Completely Fail

    Construction loans require expertise banks don't possess. Here's what goes wrong with bank construction financing:

    Inadequate draw schedules that don't align with construction reality, forcing you to self-finance between draws.

    Inflexible rate products that don't protect against rate increases during long construction periods.

    Poor contractor approval processes limiting your builder choices and increasing costs.

    Surrey mortgage brokers specializing in construction understand local building timelines, work with approved contractor networks, and structure draws that maintain cash flow throughout your build process.

    When Banks Might Make Sense (Rare Cases)

    Banks work for straightforward financing: stable employment, excellent credit, 20% down payment, standard residential properties under $1 million.

    If you fit this profile perfectly and have an existing banking relationship with preferential rates, banks can offer faster processing for simple transactions.

    However, even "simple" Surrey transactions often involve complexities like:

    • Secondary suites requiring rental income calculations
    • Strata properties with unique bylaws
    • Properties requiring immediate minor renovations
    • First-time buyer programs with specific requirements

    These situations benefit from mortgage broker expertise even when they seem straightforward.

    Your Next Steps for Complex Financing Success

    Step 1: Honestly assess your financing complexity. Self-employed? Building or renovating? Investment property? Credit challenges? These require specialized expertise.

    Step 2: Gather comprehensive documentation. Complex financing succeeds with thorough preparation: corporate tax returns, construction contracts, rental agreements, bank statements showing seasonal income patterns.

    Step 3: Contact a specialized Surrey mortgage broker before approaching banks. We'll assess your situation, explain realistic approval odds, and prevent credit report damage from multiple bank rejections.

    Step 4: Use our mortgage calculators to understand financing requirements for your specific situation, whether construction draws or investment property cash flows.

    The difference between mortgage broker Surrey expertise and big bank limitations often determines whether you get approved or face months of rejection and frustration. Smart Surrey buyers choose specialists who understand complex financing from day one.

    Your complex financing situation isn't impossible: it just requires the right expertise and lender relationships that only specialized mortgage brokers provide.