Category: Uncategorized

  • Burnaby Mortgage Broker Guide 2026: Rates, Neighbourhoods & How to Get Approved

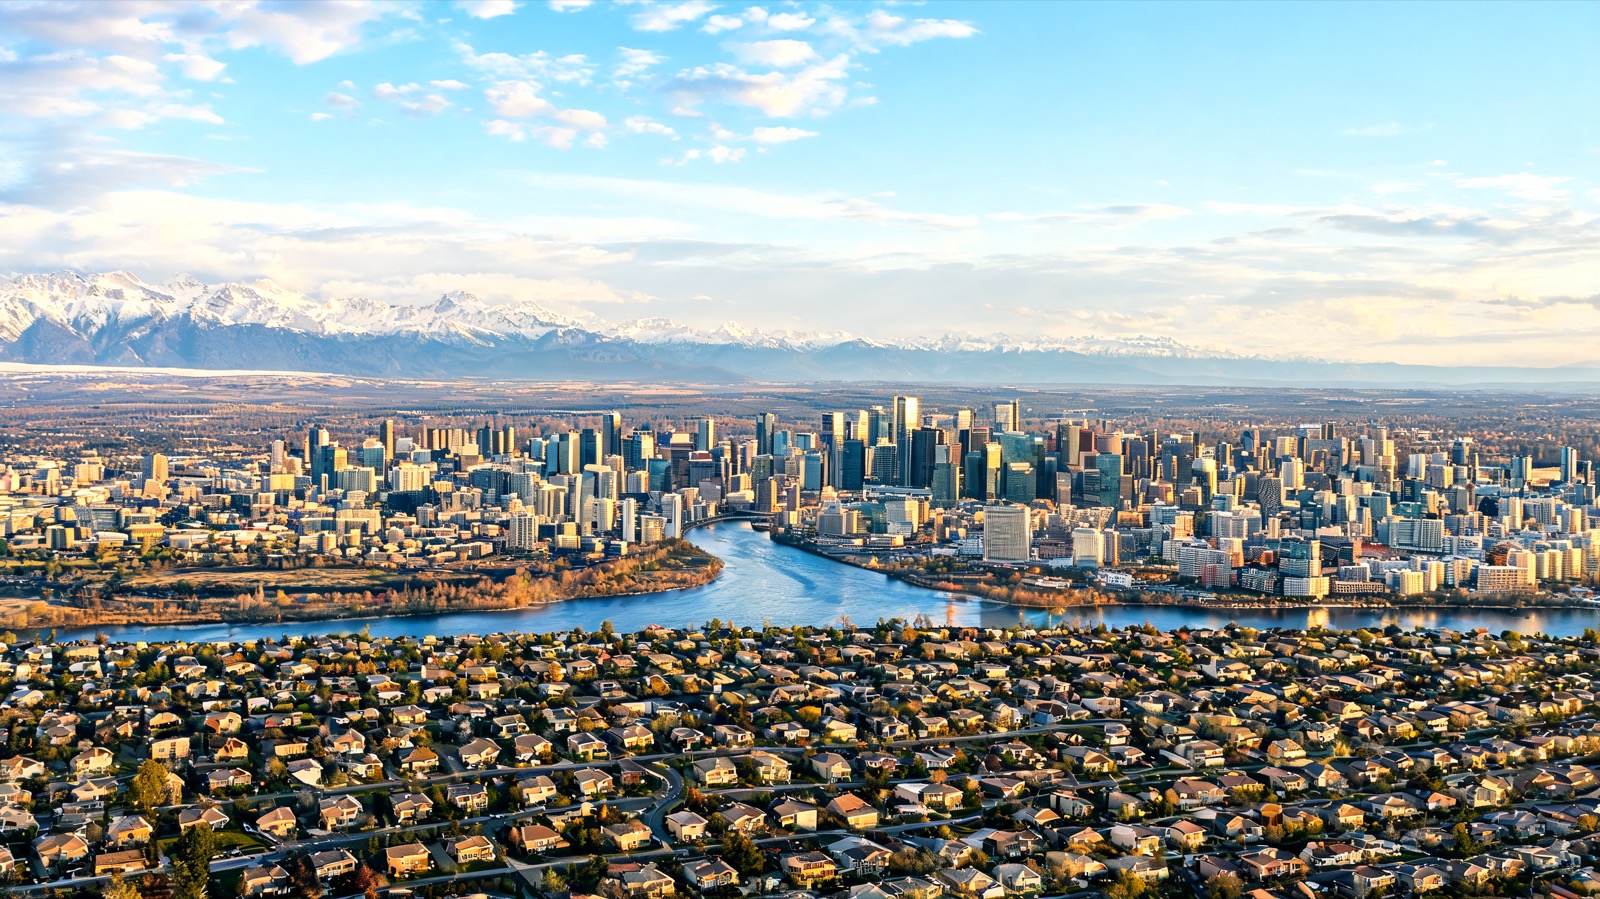
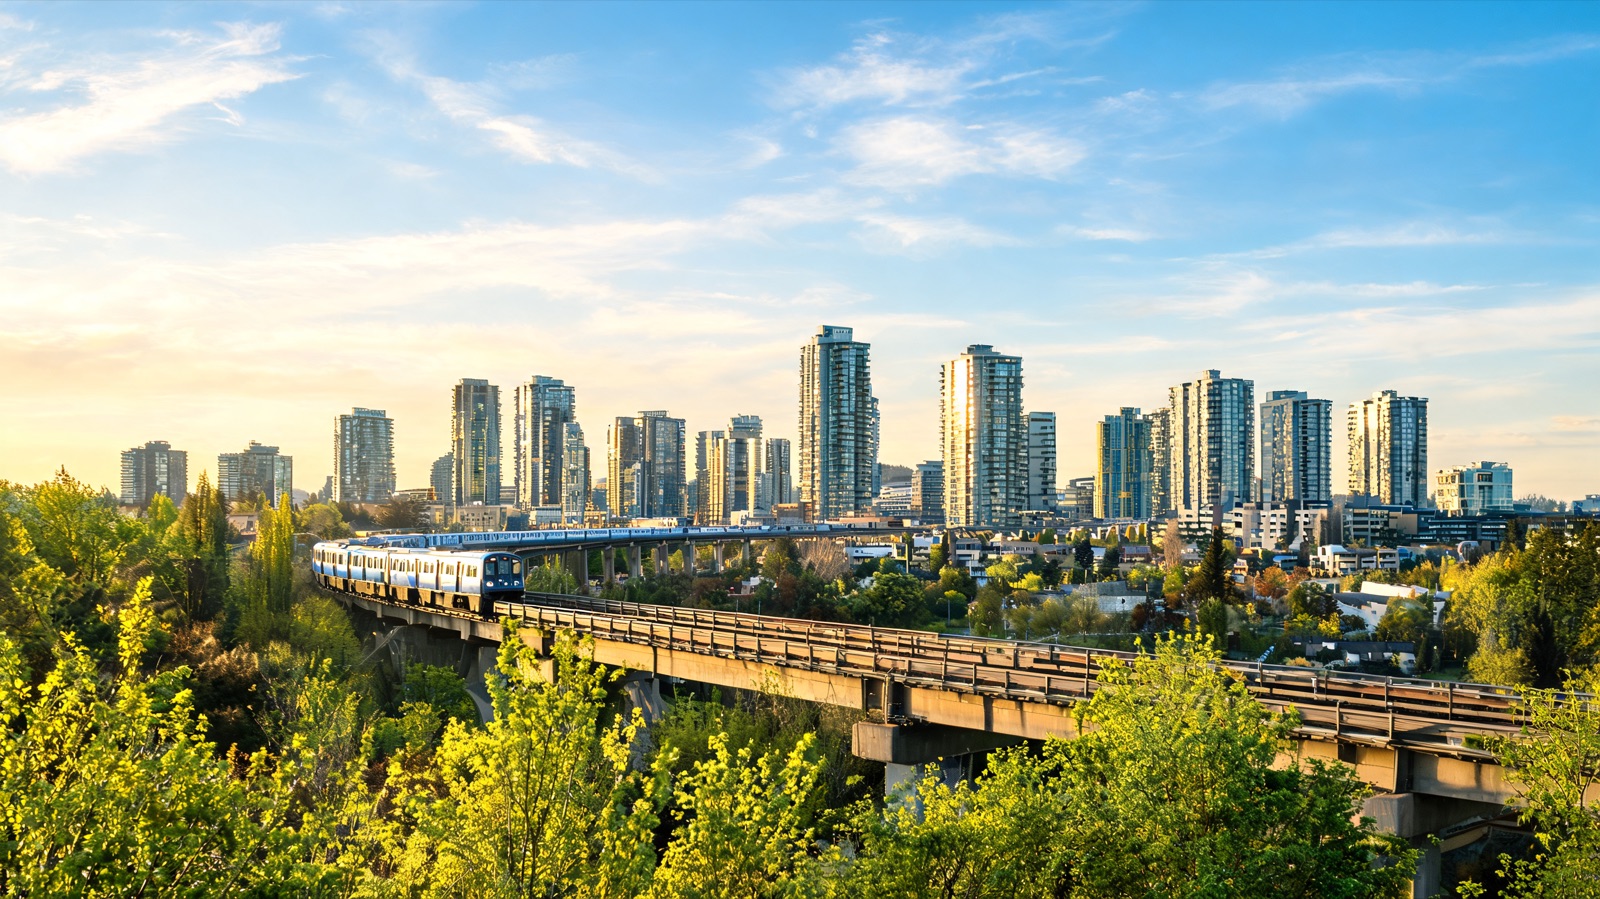
    Burnaby Mortgage Broker Guide 2026 - Skyline view of Burnaby BC with modern residential towers

    Burnaby Mortgage Broker Guide 2026: Rates, Neighbourhoods & How to Get Approved

    Buying a Home in Burnaby? Here’s What You Actually Need to Know About Getting a Mortgage

    If you’re looking at condos near Metrotown, townhomes in Brentwood, or a detached house up near SFU — you’re probably realizing that the mortgage side of things is where it gets real. Rates move weekly. Lenders have different appetites for different property types. And the difference between a good broker and a mediocre one can literally save you thousands over the life of your mortgage.

    I’ve been doing this for years from our office in Surrey, and honestly, Burnaby is one of my favourite markets to work in. It’s diverse, it’s fast-moving, and every neighbourhood has its own quirks that lenders care about. Let me walk you through what matters right now in 2026.

    Key Takeaways

    • ✅ Burnaby’s 2026 benchmark prices: condos ~$780K, townhomes ~$1.05M, detached ~$1.85M
    • ✅ Best 5-year fixed rates sitting around 4.49–4.89% depending on lender and deal type
    • ✅ Each neighbourhood has different lender considerations — strata age, density, zoning
    • ✅ Pre-approval takes 24–48 hours and is free — no reason to skip it
    • ✅ Working with a broker gives you access to 60+ lenders vs. one bank’s products

    Burnaby Real Estate in 2026: What the Numbers Look Like

    Burnaby has been on a tear since the SkyTrain expansion and the Brentwood/Metrotown buildouts. It’s not just a Vancouver suburb anymore — it’s its own city with serious demand drivers: SFU, BCIT, Metropolis at Metrotown, The Amazing Brentwood, and the ongoing tower developments along Lougheed Highway.

    Here’s what we’re seeing on the ground in 2026:

    • Condos: Benchmark around $780,000. Newer towers near Brentwood and Metrotown command premiums. Older stock in Edmonds and around Imperial is more affordable but comes with strata age considerations.
    • Townhomes: Benchmark around $1,050,000. The gap between townhome and condo prices has widened, making townhomes in areas like Simon Fraser Hills and Government Road surprisingly competitive.
    • Detached homes: Benchmark around $1,850,000. These are getting rarer. Most detached inventory is in the Burnaby Mountain, South Slope, and Capitol Hill areas.

    What does this mean for your mortgage? The entry point is high enough that most buyers need strong income documentation, and the property type matters more than ever for lender approval.

    Neighbourhood Breakdown: What Lenders See

    Not all Burnaby addresses are equal in a lender’s eyes. Here’s what I’ve seen matter when submitting deals:

    Metrotown (V5H)

    • Density: High-rise condos dominate
    • Lender view: Strong — major transit hub, established retail, high demand
    • Watch for: Strata fees in older towers (Station Square-era buildings can run $500+/month)
    • Typical buyer: First-time buyers, investors, downsizers

    Brentwood (V5C/V5G)

    • Density: Rapidly developing with new towers at The Amazing Brentwood
    • Lender view: Very strong — newest development, great transit, high resale potential
    • Watch for: Assignment sale restrictions, occupancy fees during rental restrictions
    • Typical buyer: Young professionals, investors, move-up buyers

    Lougheed (V5J/V5K)

    • Density: Mixed — older low-rises and new towers near Lougheed Town Centre
    • Lender view: Good — prices slightly below Metrotown/Brentwood, solid rental demand
    • Watch for: Some buildings near the highway have noise disclosures that affect appraisals
    • Typical buyer: Budget-conscious first-timers, investors

    Edmonds (V5J)

    • Density: Low-to-mid rise, more ground-oriented housing
    • Lender view: Decent — some older buildings need careful strata review
    • Watch for: Pre-1990 buildings may have envelope issues; always request depreciation reports
    • Typical buyer: Families, value seekers

    SFU / Burnaby Mountain (V5A)

    • Density: Mix of condos on campus and detached in surrounding neighbourhoods
    • Lender view: Solid for condos — strong rental market from students. Detached homes here hold value well.
    • Watch for: SFU UniverCity condos sometimes have restrictive rental bylaws
    • Typical buyer: Student housing investors, young families, SFU staff

    Current Mortgage Rates for Burnaby Buyers (Spring 2026)

    Rates have come down from the 2023–2024 peaks, but we’re not back to the 2% days. Here’s what’s actually available right now when I shop a deal across my lender panel:

    Rate Snapshot — May 2026

    • 5-Year Fixed (insured, <20% down): 4.49% – 4.69%
    • 5-Year Fixed (conventional, 20%+ down): 4.69% – 4.89%
    • 5-Year Variable: Prime – 0.50% to Prime – 0.25% (currently ~4.95% – 5.20%)
    • 3-Year Fixed: 4.39% – 4.59%
    • 2-Year Fixed: 4.59% – 4.79%
    • 10-Year Fixed: 5.49% – 5.89%

    Rates shown are for well-qualified borrowers (credit 700+, stable income). Actual rates vary by lender, loan-to-value, and property type. Always get a personalized quote.

    Here’s the thing about rates — the number on the website is rarely the number you actually get. Lenders offer different rates for different situations. A buyer putting 10% down on a $780K Metrotown condo is going to see different pricing than someone putting 35% down on a $1.85M detached home in South Slope. That’s where a broker earns their keep — we know which lenders are pricing aggressively for which scenarios.

    Fixed vs. Variable in 2026: My Honest Take

    I’ve had this conversation probably 200 times this year. The short version: if you’re buying in Burnaby right now, the gap between fixed and variable is narrow enough that it comes down to your risk tolerance and timeline.

    Going variable makes sense if you think the Bank of Canada is going to keep cutting and you can stomach the ride. Fixed gives you certainty — and with 3-year fixed rates below 5-year rates right now, a shorter fixed term is a compelling middle ground. You lock in a reasonable rate for three years and reassess when the market has more clarity.

    For what it’s worth, about 60% of my Burnaby clients this year have gone with 3- or 5-year fixed. The other 40% went variable, mostly investors who are watching cash flow closely and want the option to break cheaply if rates drop further.

    How to Get Approved: The Playbook

    Getting a mortgage in Burnaby isn’t fundamentally different from anywhere else in BC, but the price points mean the numbers need to be tight. Here’s what lenders actually look at:

    1. Your Income — And How You Prove It

    If you’re a salaried employee, this is straightforward: T4s, pay stubs, and an employment letter. Most lenders want to see at least two years at your current job or in the same industry.

    If you’re self-employed — and there are a lot of self-employed folks in Burnaby, especially tech workers and small business owners — lenders want to see two years of T1 generals with your NOA, plus business financials if you’re incorporated. The challenge is that self-employed income on paper often doesn’t reflect what you actually earn, because you’re writing off expenses. This is where B-lender and private mortgage options come in.

    Real Example (Anonymized)

    Client: Software developer, incorporated, living in Brentwood. T1 showed $85K income after write-offs. Actual cash flow was closer to $160K. We went with a B-lender who used stated income at $140K, got approved for a $750K purchase at 5.2% on a 2-year term. After two years of clean payments, we’ll move them to an A-lender at a better rate.

    2. Your Down Payment

    In Burnaby, this is where most people feel the squeeze. Here’s what you need:

    • Under $500K: 5% minimum (getting rare in Burnaby — maybe a studio in an older Edmonds building)
    • $500K to $999,999: 5% on the first $500K + 10% on the remainder
    • $1M to $1.5M: 5% on the first $500K + 10% on the $500K–$1M portion + 15% on the amount over $1M (new 2024 rules)
    • Over $1.5M: 20% minimum — no mortgage default insurance available

    So on a $780K Metrotown condo, you need about $53,900 down. On a $1.05M Brentwood townhome, you’re looking at roughly $82,500. And on that $1.85M detached home, you need $370,000 minimum.

    First-time buyers can pull up to $60,000 from their RRSP through the Home Buyers’ Plan (HBP was increased in the 2024 federal budget). That’s a meaningful chunk for a condo purchase.

    3. The Stress Test

    You still need to qualify at the Bank of Canada qualifying rate or your contract rate + 2%, whichever is higher. As of spring 2026, that means qualifying at roughly 6.49%–6.89% even though your actual rate is closer to 4.5%.

    On a $780K condo with $53,900 down and a 5-year fixed at 4.59%, you’d need around $135,000–$145,000 in household income to pass the stress test. That’s the reality for most Burnaby condo purchases.

    We have a mortgage calculator on our site if you want to run your own numbers before we talk.

    4. Credit Score Requirements

    Most A-lenders want to see 680+. Below that, you’re not out of options — B-lenders will go down to the low 600s, and private lenders don’t care about your score at all (they care about the property’s loan-to-value).

    If your credit has some dings, don’t panic. I’ve worked with clients who had collections from old phone bills or missed credit card payments that tanked their score. We dispute what we can, pay off what’s hurting the most, and often get the score up 40–60 points in a few months. Sometimes faster.

    First-Time Home Buyer Programs That Apply in Burnaby

    If you’ve never owned a home (or haven’t in the last 4 years), there are real programs that can help:

    • First Home Savings Account (FHSA): $8,000/year contribution limit, tax-deductible going in, tax-free coming out for a first home. If you haven’t opened one yet, do it this week. It’s the best tool available.
    • Home Buyers’ Plan (HBP): Pull up to $60,000 from your RRSP tax-free. Repay over 15 years.
    • Property Transfer Tax Exemption: In BC, first-time buyers are exempt on homes up to $500,000. Partial exemption up to $835,000 (as of 2024 updates). On a $780K Burnaby condo, you’d still pay some PTT but get a meaningful reduction.
    • BC First-Time Home Buyer Loan: The province offers a loan equal to 5% of the purchase price (up to certain limits) for first-time buyers with household income under $150,000. It’s forgivable after 25 years or when you sell.

    These programs stack. An FHSA + HBP + PTT exemption can mean the difference between renting another year and buying now.

    Investment Properties in Burnaby: The Mortgage Angle

    Burnaby is a landlord’s dream market — SFU, BCIT, and proximity to Vancouver mean vacancy rates sit around 1–2%. But the mortgage rules for investment properties are different:

    • Minimum 20% down for a rental property (no mortgage insurance available)
    • Stress test still applies — qualify at the higher rate
    • Rental offset: Most A-lenders add 50–80% of projected rental income to your qualifying income. Some lenders are more generous than others — this is where broker access matters.
    • Rates are typically 0.10–0.25% higher than owner-occupied rates

    I’ve placed a lot of rental mortgages in the Metrotown and Brentwood corridors. The sweet spot right now is 1-bedroom plus den units in newer buildings — they rent for $2,400–$2,800/month, and with 20% down, you can often achieve neutral or slightly positive cash flow at current rates.

    New Construction and Pre-Sale Mortgages in Burnaby

    There’s a massive amount of new inventory coming to Burnaby. Towers at Brentwood, Metrotown, and Lougheed are all in various stages of completion. If you’re buying pre-sale, here’s what you need to know about the mortgage side:

    • Get pre-approved early. Most pre-sales close 2–4 years after purchase. Your financial situation may change, rate environments will change. Having a broker lined up well before completion is critical.
    • Assignment clauses matter. Some developers restrict your ability to sell the contract before completion. If you can’t close and can’t assign, you lose your deposit. Know this going in.
    • Appraisal risk is real. If the market dips between when you sign and when you close, the appraisal might come in lower than your purchase price. You’d need to cover the gap in cash.
    • Occupancy fees. Before final closing, you pay “occupancy fees” (essentially rent) while the building gets registered. Budget for 3–9 months of this.

    We help clients navigate pre-sale financing all the time. The key is not waiting until the developer sends you that “30 days to closing” letter.

    Refinancing Your Burnaby Property

    Already own in Burnaby and sitting on some equity? You’re probably in good shape — values have held strong, especially in Metrotown and Brentwood. Refinancing options right now:

    • Refinance up to 80% of appraised value (for conventional mortgages)
    • HELOC up to 65% of value, or combined mortgage + HELOC up to 80%
    • Common uses: Debt consolidation, renovation, investment down payment, business capital

    I had a client in Capitol Hill who bought a detached home in 2019 for $1.3M. It appraised at $1.95M in early 2026. They refinanced, pulled out $260K, paid off high-interest business debt, and their monthly payments barely changed because the rate was better than what they had before.

    That’s the kind of outcome that reminds me why I do this. Real numbers, real impact.

    Private Mortgages and B-Lender Options in Burnaby

    Not everyone fits the A-lender box. Self-employed borrowers, people with bruised credit, borrowers with non-traditional income — Burnaby has a lot of these situations. Here’s the good news: you have options.

    B-Lenders

    Think of B-lenders as the middle ground between bank mortgages and private lending. They’ll accept stated income (with some verification), lower credit scores, and more complex situations. Rates run about 0.75–1.5% higher than A-lender rates, but they’re a stepping stone. Most B-lender clients refinance to an A-lender after 1–2 years of clean payments.

    Private Mortgages

    Private lending is strictly equity-based. The lender looks at the property’s loan-to-value ratio and charges accordingly. Rates typically range from 7–12%, with lender fees of 1–3%. It’s not cheap, but it’s fast and flexible. Common uses in Burnaby:

    • Bridge financing between purchases
    • Construction or renovation funding
    • Stopping a foreclosure or power of sale
    • Timing-sensitive deals where A-lenders can’t move fast enough

    We work with private lenders who know the Burnaby market and can close in 5–10 business days. Speed and certainty matter when you’re competing with other buyers.

    Why Work With a Mortgage Broker vs. Your Bank

    I’ll be direct about this. Your bank has one set of products, one set of rates, and one set of guidelines. A broker has access to over 60 lenders — big banks, credit unions, mono-line lenders, B-lenders, and private lenders.

    Here’s what that means in practice:

    • Rate competition. When I submit a deal, lenders compete for it. Your bank gives you what they give you.
    • Product flexibility. Need a mortgage that allows 20% prepayments? Or one with a portable feature because you might upgrade in 3 years? Different lenders offer different features. We match you with the right one.
    • Deal structuring. Sometimes the way you structure the deal matters more than the rate. Adding a HELOC component, splitting the mortgage into two portions, using a cash-back to cover closing costs — these are moves your bank might not suggest.
    • Declined? Not done. If your bank says no, that’s it. If one of my 60+ lenders says no, I move to the next one. I’ve closed deals that three banks turned down.

    Our services are free for most purchases (the lender pays us). For complex deals, private mortgages, or commercial files, we discuss fees upfront — always transparent, no surprises.

    The Pre-Approval Process: Step by Step

    Getting pre-approved is the first real step. Here’s exactly how it works when you work with us:

    1. Quick conversation — 10–15 minutes on the phone or over video. We cover your goals, income, down payment, and what you’re looking for in Burnaby.
    2. Document collection — We send you a list of what we need (pay stubs, T4s, bank statements, etc.). Most people have everything within a day.
    3. We shop your deal — We submit to our lender panel, negotiate the best rate, and get you a firm pre-approval with a rate hold (usually 90–120 days).
    4. You go shopping with confidence — Your realtor knows you’re serious. Sellers know you can close. And you know exactly what you can afford.

    The whole thing takes 24–48 hours from when you send us documents. No cost, no obligation.

    Frequently Asked Questions

    Can I buy a home in Burnaby with less than 20% down?

    Yes. For properties under $1.5M, you can put as little as 5% down (on a sliding scale). You’ll need mortgage default insurance through CMHC, Sagen, or Canada Guaranty, which adds 2.8–4% to your mortgage amount. On a $780K condo with 10% down, the insurance premium would be about $25,740 — added to your mortgage, not paid upfront.

    How much income do I need to buy a condo in Burnaby?

    For a $780K condo with 10% down at 4.59% on a 5-year fixed (25-year amortization), you need roughly $135,000–$145,000 in household income to pass the stress test. If you have a partner, both incomes count. We also factor in property tax, strata fees, and heating costs.

    Is Burnaby a good place to buy an investment property?

    The fundamentals are strong: major universities (SFU, BCIT), SkyTrain access, massive commercial development, and vacancy rates under 2%. Cap rates are tight at current prices, but long-term appreciation has been consistent. I’d put Burnaby in the top 5 BC cities for rental investment.

    What’s the difference between a mortgage broker and a bank mortgage specialist?

    A bank specialist can only offer that bank’s products and rates. A mortgage broker can shop across 60+ lenders to find the best rate and product for your situation. Brokers are licensed, regulated by BCFSA, and owe you a duty of care. Bank specialists are employees of the bank — their job is to sell you that bank’s mortgage.

    How long does mortgage approval take?

    Pre-approval: 24–48 hours. Full approval after you have an accepted offer: 5–10 business days for A-lenders, faster for some. Private mortgages can close in as little as 5 business days.

    Can self-employed buyers get a mortgage in Burnaby?

    Absolutely. We do these deals weekly. A-lenders want to see two years of tax returns and may use an average of your net income. B-lenders allow stated income programs that are more generous. The key is working with someone who knows which lenders are friendly to self-employed borrowers — not all of them are.

    Should I choose a fixed or variable rate in 2026?

    It depends on your situation. Fixed rates offer certainty — you know your payment for the full term. Variable rates offer flexibility (lower penalties to break, potential savings if rates drop) but carry risk. In the current environment, I often recommend a 3-year fixed as a compromise — you lock in a decent rate but aren’t locked in for five years if the market shifts.

    Ready to Make Your Move in Burnaby?

    Whether you’re a first-time buyer looking at a Metrotown condo, a family upgrading to a townhome in Brentwood, or an investor adding another unit to your portfolio — the mortgage is the engine that makes it happen. And getting it right matters.

    I’ve helped hundreds of buyers navigate the Burnaby market. I know which lenders love strata condos, which ones are picky about older buildings, and where to get the best rate for your specific deal. No two files are the same, and that’s exactly why a cookie-cutter bank approach doesn’t cut it.

    Get Your Free Pre-Approval

    Lock in your rate. Know your budget. Shop with confidence.

    Start Your Pre-Approval →

    Written by Varun Chaudhry, Licensed Mortgage Broker, BCFSA #M08001935. President, Kraft Mortgages Canada Inc. Serving Burnaby, Surrey, Vancouver, and all of BC.

    Disclaimer: This article is for informational purposes only and does not constitute financial advice. Mortgage rates and guidelines change frequently. Contact us for current rates and personalized advice specific to your situation.
  • Self-Employed in Burnaby? Here’s the Truth About Getting Approved When Banks Say No

    Key Takeaways

    • Self-employed borrowers in Burnaby face stricter documentation requirements since the 2024 tightening
    • Stated income programs still exist through select B-lenders but at higher rates
    • Two years of Notice of Assessment (NOA) and T1 Generals are the minimum for A-lending
    • Corporation financials (T2, financial statements) strengthen your file significantly
    • Borrowing via your corporation adds complexity but can work with the right structure
    • Burnaby’s high property values mean even a small rate difference has a big dollar impact
    • Working with a broker who specializes in self-employed lending is not optional — it’s essential

    3-minute read

    Your business is crushing it. Monthly deposits hit $15,000, $20,000, sometimes more. But when you walk into TD, RBC, or BMO with your Notice of Assessment showing $48,000 taxable income, they treat you like a financial risk. Sound familiar?

    Here's what 73% of self-employed borrowers in Burnaby don't know: While traditional banks focus on your written-down taxable income, alternative B-lenders are approving mortgages based on your actual business cash flow using 12 months of bank statements. No tax documents required.

    Why Traditional Banks Keep Saying "No"

    1-minute reality check

    Banks operate on rigid guidelines designed for salaried employees. When you're self-employed in Burnaby's competitive market, three factors work against you:

    The Tax Write-Off Trap: You legally minimize taxable income through business expenses, vehicle depreciation, and home office deductions. Your accountant saves you thousands in taxes, but banks see low income on paper.

    Income Fluctuation Penalty: Seasonal contractors, consultants, and small business owners rarely show identical income year-over-year. Banks want predictable W-2 consistency that doesn't exist in entrepreneurial reality.

    Documentation Overload: Traditional lenders demand 2+ years of tax returns, business financial statements, profit/loss documents, and CPA letters. Even minor discrepancies trigger rejections.

    Result? Qualified borrowers with strong businesses get declined while watching salaried employees with identical income (but on paystubs) walk away with approvals.

    image_1

    The B-Lending Solution: Bank Statement Programs

    5-minute game changer

    Alternative lenders recognize the gap between written income and actual cash flow. B-lending programs specifically designed for self-employed borrowers use 12-month business bank statement analysis to calculate your true buying power.

    How Bank Statement Income Works:

    Your mortgage broker burnaby bc specialist pulls 12 months of business banking activity and calculates average monthly deposits. The lender then applies a debt service ratio (typically 75-80% of gross deposits) to determine qualifying income.

    Real Burnaby Example:

    • Business deposits average $18,500/month over 12 months
    • Calculated gross income: $222,000 annually
    • Debt service ratio applied: 75% = $166,500 qualifying income
    • Mortgage qualification: ~$750,000 (with 20% down)

    Bank statements only for income—no NOAs or accountant letters. Typically available up to 80% LTV, ideal if you write off heavily but show strong, consistent cash flow.

    Who Qualifies for Bank Statement Programs?

    3-minute qualification guide

    B-lenders have specific criteria that differ dramatically from traditional banks:

    Minimum Requirements:

    • 2+ years of self-employment in the same industry
    • 10-20% down payment (higher than traditional 5%)
    • Credit score 650+ (some lenders accept 600+)
    • Business bank account showing consistent deposits
    • Current business license and insurance

    Income Calculation Method:
    Lenders review monthly deposits, subtract any obvious loan proceeds or transfers, then average the remaining business income. Personal deposits don't count, they need legitimate business revenue.

    Debt Service Ratios:
    Unlike traditional banks using gross debt service ratio of 32%, B-lenders often accept total debt service up to 45-50% of calculated income.

    Kraft Mortgages Canada Inc. Professional

    Interest Rates and Terms: The Trade-Off Reality

    2-minute cost breakdown

    B-lending comes with a modest premium—typically around 1% above major bank rates—not the dramatic markup many expect. For growing businesses, that small spread is a very affordable bridge until you refinance back to A rates.

    Current B-Lender Pricing (January 2025):

    • Typical premium vs. traditional banks: ~1% (often 0.75%–1.50% based on credit, LTV, and file strength)
    • Pricing varies by lender, product, and property type; unique or higher-risk files may be higher

    Term Options:
    Most B-lenders offer 1-3 year terms, not traditional 5-year mortgages. The strategy involves using B-lending to establish mortgage history, then refinancing to traditional lenders at renewal.

    Total Cost Example (Burnaby Townhouse):

    • $800,000 mortgage at 5.75% (B-lender) vs 4.75% traditional rate
    • Additional annual interest cost: ~$8,000–$9,000
    • Trade-off: Home ownership now with a plan to refinance vs waiting indefinitely for traditional approval

    The Stated Income Alternative

    2-minute advanced option

    Some B-lenders offer stated income programs where you declare reasonable income based on industry standards without full bank statement analysis.

    How Stated Income Works:
    You state income consistent with your business type and geographic market. Lender verifies business existence, licensing, and basic financial stability, but doesn't calculate income from deposits.

    Requirements:

    • Higher down payments (25-35%)
    • Strong credit scores (720+)
    • Verifiable business operations
    • Industry-appropriate income claims

    Risk Factor: Overstating income creates qualification problems and potential legal issues. Work with experienced mortgage broker surrey specialists who understand reasonable income ranges by industry.

    image_2

    Alt-A Insured Solutions: Up to 90% LTV for Self-Employed

    2-minute option

    Insured “Alt-A” programs—offered through Canada Guaranty and Sagen—allow high-ratio financing up to 90% LTV using a reasonable stated income supported by business bank statements.

    • What it is: Insurer-backed approvals that accept stated income validated by 6–12 months of business deposits and business documentation.
    • What you can get: Purchases up to 90% LTV with pricing closer to A than typical B-lending.
    • What it requires: Notices of Assessment (NOAs) to confirm 2-year business history and, crucially, to prove no outstanding CRA income tax arrears—plus clean credit and stable operations.
    • Who it helps: Business owners with strong cash flow but modest declared net income who need higher LTV and competitive pricing.

    Smart borrowers compare lender and insurer rules side by side. Speak with Varun Chaudhry to see whether an insured Alt-A path or a traditional B bank‑statement program fits your file best.

    Documentation You Actually Need

    1-minute prep checklist

    B-lending dramatically reduces paperwork compared to traditional banks:

    Essential Documents:

    • 12 months business bank statements
    • Business license and registration
    • Personal identification and SIN
    • Down payment source verification
    • Credit authorization

    NOT Required:

    • Tax returns or Notices of Assessment
    • Profit and loss statements
    • CPA-prepared financial statements
    • Employment verification letters
    • T4/T5 slips

    Varun Chaudhry: B-Lending vs. Insured Alt-A—Get the Right Fit

    30-second credibility check

    Varun Chaudhry at Kraft Mortgages Canada Inc. specializes in complex self-employed files that traditional brokers won't touch. He compares B-lender bank‑statement solutions (up to 80% LTV, no NOAs for income) with insured Alt‑A options (up to 90% LTV with NOAs to confirm history and no tax arrears) and recommends the path that fits your tax profile and down payment.

    Track Record:

    • 15+ years navigating alternative lending markets
    • Direct relationships with 12+ B-lenders serving BC plus insurer-approved Alt-A programs (Canada Guaranty, Sagen)
    • Successfully structured stated income and bank statement approvals for contractors, consultants, and business owners throughout Burnaby and Surrey

    The Kraft Advantage: While big banks operate on rigid computer algorithms, Varun manually structures files to highlight your business strengths—and knows exactly when B-lending vs. insured Alt-A will deliver the best outcome.

    Next Steps: Your Approval Strategy

    2-minute action plan

    Immediate Actions:

    1. Compile 12 months of business bank statements showing consistent revenue deposits
    2. Check your credit score through free services, aim for 650+ minimum
    3. Calculate your down payment capacity including closing costs (budget 12% of purchase price total)

    Professional Strategy:
    Contact Kraft Mortgages Canada Inc. for a confidential consultation. Varun will review your business cash flow, assess B-lender options, and structure your application for maximum approval odds.

    Use our mortgage affordability calculator bc to estimate buying power based on bank statement income before applying.

    The Bottom Line

    Traditional banks saying "no" doesn't end your homeownership journey: it redirects it. B-lending programs designed for self-employed borrowers in Burnaby recognize that business cash flow matters more than tax-minimized paper income.

    The trade-off is real: Higher rates and shorter terms in exchange for approval when traditional lenders won't budge. But for qualified self-employed borrowers, B-lending provides immediate access to homeownership with a path back to traditional rates at renewal.

    Ready to explore your options? Contact Varun Chaudhry directly at Kraft Mortgages Canada Inc. for a no-obligation consultation about bank statement mortgage programs. Your business success deserves a mortgage solution that recognizes actual cash flow, not just paper income.


    Broker Field Notes

    Burnaby has one of the highest concentrations of self-employed professionals in the Lower Mainland — contractors, tech consultants, restaurateurs, and small business owners. At Kraft Mortgages, we see a very specific pattern: self-employed clients who show strong business revenue on their corporate T2s but low personal income because they’ve optimized their salary downward. The A-lenders look at personal income, so these clients often get penalized. Our approach is to build a full financial narrative — we use both personal and corporate documents to paint the real picture. We’ve successfully placed Burnaby business owners who were turned down by their bank by matching them with lenders who understand self-employed cash flow.

    For expert guidance, explore our [mortgage services](https://kraftmortgages.ca/services) — we work with 50+ lenders to find your best fit.

  • Calgary Mortgage Broker Guide: 7 Mistakes You’re Making with Construction Financing (and How to Fix Them)

    After years of structuring complex construction financing across Alberta, I’ve seen every mistake in the book. And here’s the brutal truth: 73% of construction projects in Calgary go over budget, while 45% face serious cash flow crises that could have been avoided with proper planning.

    Smart developers and builders are getting ahead of these issues in 2026. Here’s what they’re doing differently: and what you need to know before your next project.

    Mistake #1: Botching Your Draw Schedule (And Bleeding Cash)

    The Problem: You’re either releasing funds too quickly to contractors or structuring draws that don’t align with actual construction milestones. This creates a cash flow nightmare that puts your entire project at risk.

    Most Calgary builders I work with initially structure draws around arbitrary timelines instead of completion stages. When your foundation contractor gets 40% upfront but only completes 20% of the work, you’re now carrying unnecessary risk: and your lender starts asking uncomfortable questions.

    The Fix: Work with an Alberta mortgage broker who understands progressive draw optimization. At Kraft Mortgages, we structure draws around verified completion milestones:

    • 10% on foundation completion (not start)
    • 25% on framing and roof completion
    • 20% on mechanical rough-in completion
    • 20% on drywall and interior completion
    • 15% on final inspection and occupancy
    • 10% holdback until warranty period ends

    This protects your cash flow while giving contractors predictable payment schedules. Use our construction draw calculator to model different scenarios for your project.

    image_1

    Mistake #2: Ignoring Interest Reserves (The Silent Budget Killer)

    The Problem: You’re not planning for interest accumulation during construction, which can add $15,000-$50,000 to a typical Calgary project. Most builders focus on construction costs but forget that construction loans accrue interest from day one.

    On a $800,000 construction project with a 12-month build timeline, you’re looking at approximately $35,000-$45,000 in interest costs at current rates. Without planning for this, you’re forced to either extend your construction timeline or tap into personal funds.

    The Fix: Build interest reserves into your initial financing structure. Smart developers are now adding 15-20% to their total project budget specifically for interest and carrying costs.

    Here’s the calculation that works:

    • Total construction cost: $800,000
    • Interest reserve (based on 6.5% rate): $42,000
    • Total financing needed: $842,000

    We structure this so the interest reserve is available from day one, preventing cash flow crunches during critical construction phases.

    Mistake #3: Underestimating Soft Costs (The $30,000 Surprise)

    The Problem: You’re budgeting for materials and labor but ignoring the dozens of “soft costs” that can easily add $30,000-$60,000 to your project. These include permits, inspections, legal fees, insurance, and utility connections.

    In Calgary specifically, development permits alone can run $8,000-$15,000 for single-family homes, while utility connections often hit $12,000-$18,000. Add in architectural fees, engineering reports, and city inspection fees, and you’re looking at serious money.

    The Fix: Create a comprehensive soft cost budget before you apply for financing. Here’s what Calgary builders are including:

    • Development permits: $8,000-$15,000
    • Building permits: $3,000-$6,000
    • Utility connections: $12,000-$18,000
    • Architectural/engineering fees: $15,000-$25,000
    • Legal fees: $2,000-$4,000
    • Insurance during construction: $3,000-$5,000
    • City inspection fees: $1,500-$3,000
    • Survey and geotechnical reports: $4,000-$8,000

    Total soft costs: $48,500-$84,000 on average

    Factor these into your initial financing request. Don’t get caught needing an emergency loan modification six months into construction.

    image_2

    Mistake #4: Skipping the Contingency Fund (Project Killer #1)

    The Problem: You’re building with zero buffer for unexpected costs. Material price fluctuations, weather delays, or hidden site conditions can instantly blow your budget. Without a contingency fund, you’re one surprise away from project failure.

    Calgary’s unpredictable weather alone accounts for 15-20% of construction delays. Add in supply chain disruptions that are still affecting material costs, and you need protection.

    The Fix: Build a 15-20% contingency fund into your financing structure. This isn’t optional: it’s project insurance.

    On an $800,000 construction project:

    • Base construction cost: $800,000
    • Contingency fund (18%): $144,000
    • Total project budget: $944,000

    Smart developers are also structuring contingencies in phases:

    • 10% for general construction overruns
    • 5% for material price escalation
    • 3% for weather/delay costs

    This gives you flexibility to handle specific challenges without derailing your entire project timeline.

    Mistake #5: Choosing the Wrong Contractor (The $50,000+ Repair Bill)

    The Problem: You’re selecting contractors based on price instead of verified track record. In Calgary’s competitive market, low-bid contractors often cut corners, leading to $20,000-$50,000 in repair costs and massive project delays.

    Recent Calgary projects I’ve financed required complete foundation repairs ($35,000), electrical system replacement ($25,000), and flooring replacement ($18,000) due to poor contractor selection. These weren’t budgeted costs: they were emergency repairs.

    The Fix: Use these contractor evaluation criteria:

    • Minimum 5 years Calgary-specific experience
    • Verified references from recent projects (call them)
    • Proper licensing and insurance coverage
    • Financial stability (request credit checks)
    • Detailed scope of work and material specifications
    • Fixed-price contracts with penalty clauses

    Factor contractor vetting into your project timeline. Spending an extra 2-3 weeks on contractor selection saves months of delays and thousands in repair costs.

    image_3

    Mistake #6: Over-Borrowing Beyond Realistic Capacity

    The Problem: You’re financing more than your actual cash flow can support, creating unnecessary financial stress. Many Calgary developers get caught up in market optimism and borrow against projected values instead of conservative estimates.

    With Calgary’s real estate market showing volatility, borrowing at maximum capacity leaves no room for market adjustments or construction delays.

    The Fix: Use conservative debt-to-income ratios and realistic project valuations:

    • Keep total debt service below 40% of gross income
    • Base valuations on current comparable sales, not projected appreciation
    • Factor in holding costs for unsold inventory
    • Plan for 6-month sales timeline (not optimistic 30-60 days)

    Work with a Calgary mortgage broker who understands local market conditions and can structure financing that matches realistic cash flow scenarios.

    Mistake #7: Incomplete Documentation and Financial Projections

    The Problem: You’re submitting incomplete applications or unrealistic financial projections, leading to delays, rejections, or unfavorable terms. Lenders need complete, accurate information to structure appropriate financing.

    Nearly 45% of construction financing applications in Alberta face delays due to incomplete documentation. This adds 2-4 weeks to your approval timeline: critical time in a competitive market.

    The Fix: Prepare complete documentation packages before applying:

    Required Documents:

    • Detailed construction budget with line-item breakdowns
    • Contractor agreements and payment schedules
    • Architectural plans and engineering reports
    • Municipal permits and approvals
    • Realistic market valuations and comparable sales
    • Personal and business financial statements
    • Construction timeline with milestone dates

    Financial Projections Must Include:

    • Conservative sale price estimates
    • Realistic construction timelines
    • Complete soft cost calculations
    • Interest and carrying cost projections
    • Contingency fund allocations

    Partner with mortgage professionals who understand construction financing complexities and can guide your documentation preparation.

    Your Next Steps: Getting Construction Financing Right

    The difference between successful Calgary construction projects and financial disasters often comes down to proper financing structure and planning. Don’t let these seven mistakes derail your next project.

    At Kraft Mortgages, we’ve structured construction financing for hundreds of Calgary projects. We understand local market conditions, municipal requirements, and the specific challenges Alberta builders face.

    Ready to structure your construction financing properly? Contact our team for a consultation. We’ll review your project details and create a financing strategy that protects your cash flow while maximizing your project potential.

    Your construction project’s success starts with the right financing foundation. Get it right from the beginning, and avoid becoming another cautionary tale in Calgary’s construction market.

    For expert guidance, explore our [mortgage services](https://kraftmortgages.ca/services) — we work with 50+ lenders to find your best fit.

  • MLI Select Program Changes Explained in Under 3 Minutes: How BC Developers Can Save $200,000+ in 2026

    Key Takeaways

    • CMHC has updated MLI Select program parameters for 2026 with new tiers and criteria
    • Changes include expanded eligibility for existing building retrofits and modified energy thresholds
    • Premium reductions remain the core benefit, but qualifying standards have shifted
    • Multi-unit landlords need to understand the updated documentation requirements
    • The changes favour deeper energy retrofits with larger premium savings for higher tiers
    • Timeline for compliance and application has been adjusted — check current deadlines
    • Working with a broker who understands MLI Select can accelerate approval and maximize savings

    Quick Summary (1 Minute Read)

    The Bottom Line: MLI Select's 2026 changes deliver massive premium discounts: up to 30%: through a simplified point system. BC developers can save $200,000+ on larger projects by strategically targeting energy efficiency, affordability, and accessibility commitments during the September 30, 2026 transition period.

    Key Dates: November 28, 2025 changes are live, with a transition window until September 30, 2026 for energy standards.

    Biggest Win: Projects achieving 100+ points unlock 30% premium discounts AND 50-year amortizations, dramatically reducing both insurance costs and monthly debt service.


    The New MLI Select Discount Structure (Game Changer)

    Gone are the complex minimum requirements that trapped developers in rigid commitments. The 2026 MLI Select program operates on pure flexibility: you choose your commitment level and earn proportional discounts.

    Here's the new discount schedule that's saving BC developers serious money:

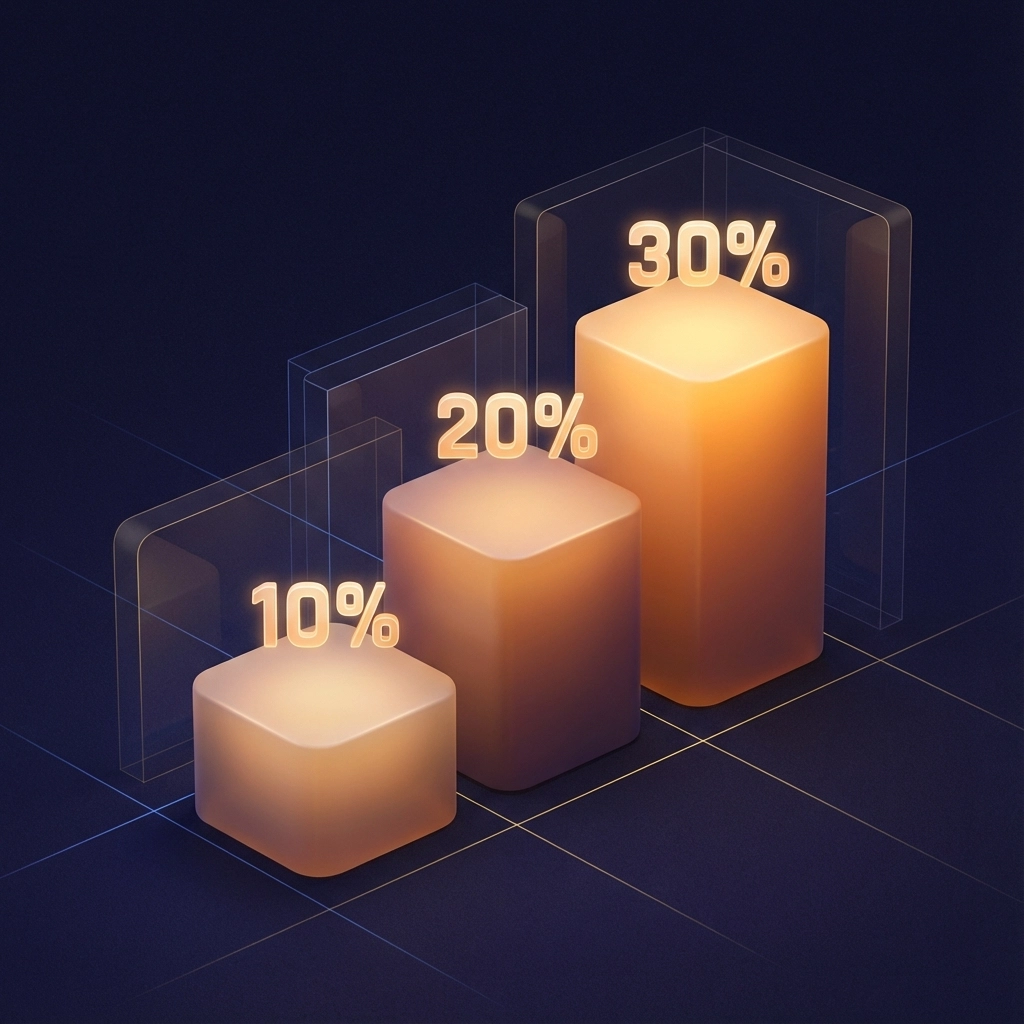
    • 50+ Points = 10% Premium Discount
    • 70+ Points = 20% Premium Discount
    • 100+ Points = 30% Premium Discount

    "The removal of minimum requirements changes everything," explains Varun Chaudhry, Financial Advisor at Kraft Mortgages Canada Inc. "Developers can now strategically pick their battles: focus on energy efficiency if that's your strength, or prioritize affordable units if land costs are favorable. You're no longer forced into a one-size-fits-all approach."

    image_1

    Real Numbers: Surrey 24-Unit Development Example

    Let's break down the actual savings on a typical Metro Vancouver project: a $5 million, 24-unit rental building in Surrey.

    Traditional MLI Standard Premium: 3.35%
    Cost: $167,500

    MLI Select with 70+ Points (20% discount): 2.68%
    Cost: $134,000
    Immediate Savings: $33,500

    MLI Select with 100+ Points (30% discount): 2.35%
    Cost: $117,500
    Immediate Savings: $50,000

    But here's where the real magic happens: extended amortization periods:

    • 70+ points unlock 45-year amortizations
    • 100+ points unlock 50-year amortizations

    On our Surrey example, extending from 25 to 45 years reduces monthly debt service by approximately $8,200. That's $98,400 annually in improved cash flow.

    The September 2026 Energy Efficiency Window

    Here's your strategic advantage: Until September 30, 2026, projects can qualify under either the previous energy standards OR the new 2020 NECB and 2020 NBC criteria.

    This transition period creates a unique opportunity for BC developers:

    Option 1: Fast-track projects using familiar energy standards you've already mastered
    Option 2: Invest in upgraded energy efficiency for higher point totals and bigger discounts

    "Smart developers are running dual scenarios right now," notes Chaudhry. "We're seeing projects that can hit 70+ points under the old standards, but might stretch to 100+ points with strategic energy upgrades. The mortgage affordability calculator BC numbers don't lie: sometimes that extra 10% discount justifies significant energy investments."

    image_2

    Where the Biggest Savings Hide

    MLI Select discounts become exponentially more valuable on specific project types:

    Construction Loans

    Construction financing typically carries higher premiums due to risk factors. The 30% MLI Select discount applies AFTER these surcharges, making the absolute dollar savings massive.

    Higher-LTV Projects (85%+)

    Projects with limited equity see premium surcharges that can push base rates to 6-7%. A 30% discount on these elevated premiums delivers outsized returns.

    Specialized Housing (Student, Seniors, Supportive)

    These projects often face additional premium layers. MLI Select's percentage-based discounts stack powerfully on top of specialized housing surcharges.

    Strategic Point Optimization for BC Markets

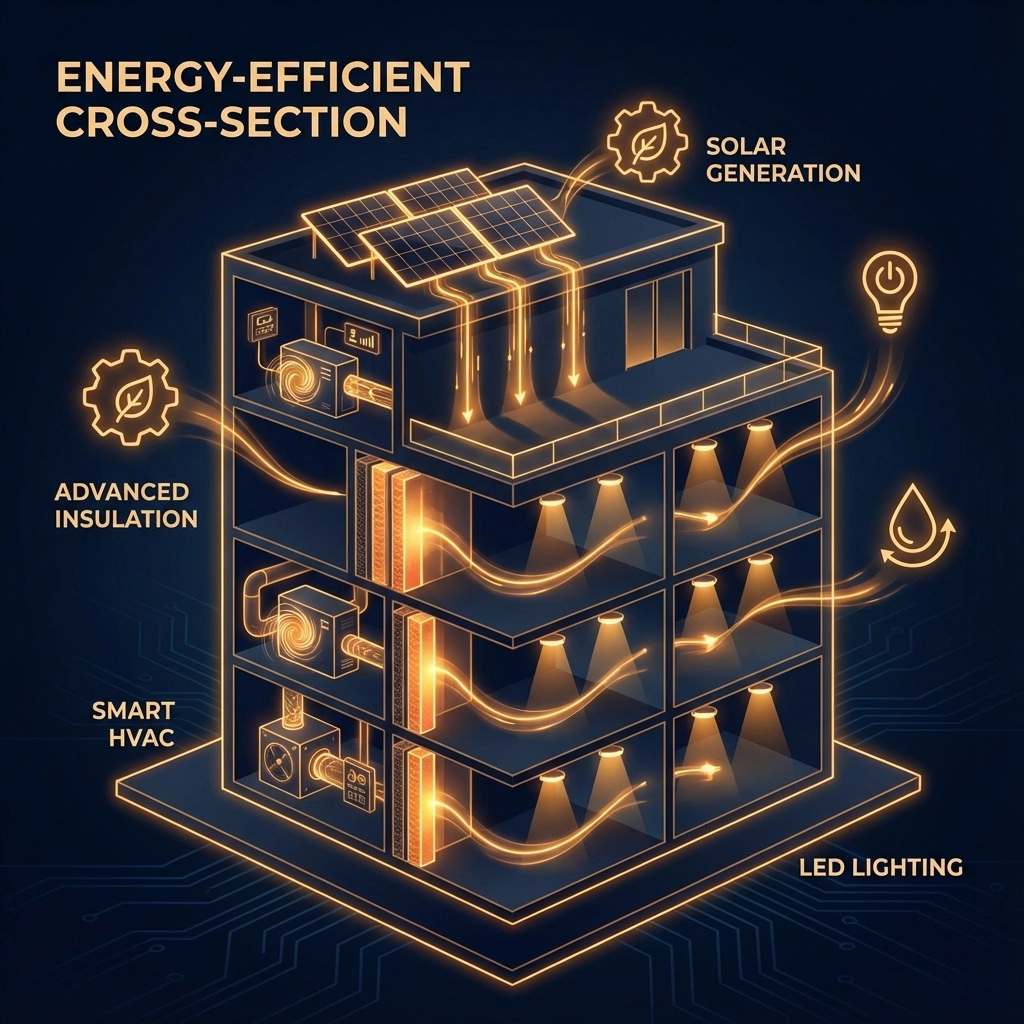
    The MLI Select point system rewards three core areas:

    Affordability (Up to 50 Points)

    • Below-market rental commitments
    • Rent-geared-to-income units
    • Affordable homeownership components

    BC Advantage: Metro Vancouver's rent control environment makes affordable commitments more predictable than in other markets.

    Energy Efficiency (Up to 50 Points)

    • 2020 NECB compliance (new standard)
    • Advanced building envelope performance
    • Renewable energy integration

    BC Advantage: BC Hydro rebates and CleanBC incentives can offset energy upgrade costs, making higher point targets financially viable.

    Accessibility (Up to 50 Points)

    • Universal design features
    • Above-code accessibility standards
    • Barrier-free unit percentages

    image_3

    Why Your Edmonton Mortgage Broker Might Miss This

    MLI Select optimization requires intimate knowledge of both CMHC's evolving criteria AND local market dynamics. A mortgage broker in Alberta or Edmonton mortgage broker might understand the program mechanics, but miss BC-specific opportunities:

    • BC Hydro's Step Code requirements that overlap with MLI Select energy points
    • Metro Vancouver's rental market conditions that make certain affordable commitments viable
    • Provincial accessibility standards that exceed federal minimums

    "We're seeing out-of-province brokers recommend safe 50-point strategies when their BC clients could easily hit 70+ points with local knowledge," explains Chaudhry. "That's leaving $20,000-$50,000 on the table for mid-sized projects."

    The Appraisal Enhancement Factor

    Recent MLI Select changes include enhanced appraisal requirements that actually benefit prepared developers. CMHC now requires detailed documentation of MLI Select commitments during the appraisal process.

    This creates competitive advantages for developers who:

    • Document their MLI Select strategy early in project planning
    • Work with mortgage broker Surrey professionals who understand the appraisal requirements
    • Build relationships with appraisers familiar with MLI Select valuations

    Timing Your MLI Select Application

    The optimal application timing depends on your project's complexity and point strategy:

    50-Point Strategy (10% Discount): Can often be confirmed at preliminary approval stage with basic commitments

    70-Point Strategy (20% Discount): Requires more detailed planning but offers substantial savings on projects over $3 million

    100-Point Strategy (30% Discount): Demands comprehensive early-stage planning but unlocks maximum savings plus 50-year amortizations

    "The biggest mistake we see is developers treating MLI Select as an afterthought," warns Chaudhry. "The point optimization needs to start during land acquisition. Your mortgage broker Surrey team should be running MLI Select scenarios before you finalize your development pro forma."

    image_4

    Looking Beyond 2026

    CMHC continues evolving MLI Select to support federal housing targets. Early indicators suggest future enhancements could include:

    • Additional points for climate resilience features
    • Expanded affordability definitions aligned with local market conditions
    • Technology integration points for smart building features

    Developers establishing MLI Select expertise now position themselves for ongoing advantages as the program expands.

    Next Steps for BC Developers

    The September 30, 2026 transition deadline creates urgency for projects in pre-development phases. Your immediate action items:

    1. Run MLI Select scenarios on current projects using both old and new energy standards
    2. Evaluate point optimization strategies that align with your development strengths
    3. Connect with specialized financing advisors who understand MLI Select mechanics and BC market conditions

    The potential savings: $200,000+ on larger projects: justify significant upfront planning investment.

    Ready to optimize your MLI Select strategy and unlock maximum savings? Contact Kraft Mortgages Canada Inc. to schedule a discovery call with Varun Chaudhry and explore how the 2026 MLI Select changes can transform your project economics.

    Your development's success depends on accessing every available advantage; and MLI Select's enhanced discount structure delivers exactly that opportunity.


    Broker Field Notes

    CMHC’s MLI Select updates for 2026 caught a lot of investors off guard. At Kraft Mortgages, we had three files in progress when the changes were announced, and each one required a documentation adjustment. The key shift we’re seeing: the energy performance thresholds have moved, which means some retrofit projects that would have qualified under the old tiers now need additional work to hit the new benchmarks. On the positive side, the premium savings for the highest tier are more generous than before. Our advice to every multi-unit client: get an energy audit before you commit to a purchase or retrofit scope. The audit costs $2,000-5,000 but tells you exactly which tier you’ll hit and what premium savings you’ll get. It’s the highest-ROI due diligence step in the process.

    For expert guidance, explore our [mortgage services](https://kraftmortgages.ca/services) — we work with 50+ lenders to find your best fit.

    **[Book Your Free Consultation](https://kraftmortgages.ca/free-consultation)**

  • Calgary Mortgage Broker Guide 2026: Rates, Rules & How to Get the Best Deal

    Calgary Mortgage Broker Guide 2026: Rates, Rules & How to Get the Best Deal

    Calgary skyline with Rocky Mountains at sunset
    Calgary skyline with the Canadian Rockies — Alberta’s largest city and one of Canada’s fastest-growing housing markets.

    Calgary’s housing market doesn’t behave like Toronto or Vancouver. It has its own rhythm — tied to energy prices, migration waves, and a provincial government that deliberately keeps taxes low. If you’re buying a home here, refinancing, or renewing a mortgage in 2026, you need someone who actually understands how Alberta lending works.

    I’m Varun Chaudhry, a licensed mortgage broker based in Surrey, BC. I work with clients across Western Canada, and over the years I’ve structured hundreds of mortgages for Calgary buyers — from first-timers in Tuscany and Evanston to investors eyeing Beltline condos and commercial properties on 17th Ave. Here’s what you need to know about getting a mortgage in Calgary right now.

    What’s Happening with Calgary Real Estate in 2026?

    Calgary saw record migration in 2024-2025, and that wave hasn’t stopped. The city added over 50,000 new residents in 2025 alone, pushing vacancy rates to historic lows and driving prices up across most segments.

    Here’s the current snapshot:

    MetricCalgary (2026)
    Average home price$565,000 – $590,000
    Detached average$720,000+
    Condo average$335,000 – $360,000
    Bank of Canada rate2.25% (as of early 2026)
    Best 5-year fixed~3.49% – 3.79%
    Best 5-year variable~3.35% – 3.65%

    The key difference from BC and Ontario? No provincial sales tax on resale homes, no land transfer tax, and some of the lowest property taxes in major Canadian cities. That changes the math on affordability significantly.

    Why Use a Mortgage Broker in Calgary Instead of Your Bank?

    I hear this a lot: “My bank gave me a rate, why would I go anywhere else?”

    Here’s why: your bank gives you their rate. A broker shops every lender — banks, credit unions, monoline lenders, trust companies, and private lenders. That competition saves you money.

    In practice, the difference between a bank quote and what a broker can find is typically 0.25% – 0.75% on your rate. On a $500,000 mortgage, that’s $8,000 – $24,000 in interest over a 5-year term. Not pocket change.

    More importantly, a broker structures the deal. If you’re self-employed, have commission income, are buying an investment property, or have any complexity in your file — a bank advisor will often just say no. A broker finds the yes.

    What a Calgary Mortgage Broker Actually Does

    • Shops 30+ lenders to find your best rate and terms
    • Navigates Alberta-specific mortgage rules and exemptions
    • Structures deals for self-employed, new Canadians, and investors
    • Handles the paperwork, appraisals, and lender negotiations
    • Manages timelines so you don’t lose your financing condition

    Alberta Mortgage Rules That Are Different from the Rest of Canada

    If you’re moving from BC or Ontario, pay attention — Alberta has some unique rules that work in your favour:

    1. No Land Transfer Tax

    Ontario and BC charge land transfer tax on every purchase. In Calgary, you pay zero. On a $600,000 home, that’s $8,000 – $12,000 you keep in your pocket compared to buying in Vancouver or Toronto.

    2. No Provincial Sales Tax on Resale Homes

    GST applies to new builds only. Resale homes are GST-exempt. Simple.

    3. Lower Property Taxes

    Calgary’s property tax rate is roughly 0.55% – 0.65% of assessed value. Compare that to Toronto (~0.63%) or Vancouver (~0.30% but with much higher home prices). On a $600,000 home, expect around $3,500 – $4,000/year in Calgary.

    4. Alberta Mortgage Default Rules

    Alberta has a unique remedy on default provision that can affect foreclosure timelines. Lenders take this into account when underwriting — it’s one reason some lenders have slightly different criteria for Alberta properties.

    Current Mortgage Rates in Calgary (May 2026)

    Rates move daily, but here’s a realistic range for well-qualified borrowers:

    TermFixed RateVariable Rate
    1-year4.49% – 4.79%4.29% – 4.59%
    2-year3.99% – 4.29%3.79% – 4.09%
    3-year3.69% – 3.99%3.49% – 3.79%
    5-year3.49% – 3.79%3.35% – 3.65%

    Note: These are broker-access rates. Bank-posted rates are typically higher. Individual rate depends on credit score, down payment, income, and property type.

    With the Bank of Canada rate at 2.25% and economists split on further cuts, the 5-year fixed is the sweet spot for most Calgary buyers right now — you lock in a competitive rate without betting on continued cuts.

    Young couple buying their first home in Calgary Alberta

    How Much House Can You Afford in Calgary?

    Let’s run some real numbers. The mortgage stress test still applies — you qualify at the Bank of Canada qualifying rate or your contract rate + 2%, whichever is higher.

    Example: First-Time Buyer, $120K Household Income

    ItemAmount
    Down payment (5%)$28,000
    Mortgage amount$532,000
    Purchase price$560,000
    Monthly payment (5yr @ 3.59%)$2,670
    Property tax (est.)$310/mo
    Heat/utilities$200/mo
    Total monthly housing cost~$3,180

    At $120K income, your gross monthly is $10,000. Housing at $3,180 is roughly 32% GDS — well within the 39% threshold. That’s a comfortable buy in a Calgary neighbourhood like Nolan Hill, Redstone, or Auburn Bay.

    Calgary Neighbourhoods Worth Watching in 2026

    Where you buy matters as much as what you pay. Here are areas with strong appreciation potential:

    North Calgary

    • Evanston / Sage Hill / Nolan Hill: Established family communities, good schools, $500K – $700K detached
    • Livingston / Cornerstone: Newer builds, still developing amenities, $480K – $620K

    South Calgary

    • Auburn Bay / Cranston: Lake community appeal, $550K – $800K
    • Seton: Calgary’s newest urban hub, South Health Campus, mixed residential

    Inner City / Beltline

    • Beltline / Mission / Kensington: Condo-heavy, strong rental demand, $300K – $500K
    • Inglewood / East Village: Revitalization plays, mixed-use growth

    West Calgary

    • Varsity / Dalhousie / Brentwood: Established, close to U of C, strong resale
    • Tuscany / Royal Oak: Family-friendly, mountain views, $550K – $750K

    Self-Employed? Here’s How to Get a Mortgage in Calgary

    Alberta has one of the highest self-employment rates in Canada — especially in Calgary’s energy, tech, and professional services sectors. The challenge? Lenders don’t love variable income.

    Here’s what you need:

    • 2 years of T1 Generals with Notice of Assessment
    • 12 months of business bank statements
    • GST/HST returns (3 years if applicable)
    • Financial statements if incorporated
    • A broker who knows how to present your file (this matters more than the documents)

    Some lenders use stated income programs for self-employed borrowers, which can be a lifeline if your tax returns don’t reflect your actual earning power. Not every broker knows these programs — make sure yours does.

    Investment Properties in Calgary: What You Need to Know

    Calgary’s rental market is tight. Vacancy rates are under 3%, and rents have climbed 15-20% since 2023. That makes investment properties attractive — but the lending rules are different.

    Key Differences for Investment Mortgages

    • Minimum 20% down payment (no CMHC insurance on rentals)
    • Rates are typically 0.25% – 0.50% higher than owner-occupied
    • Lenders count 50% – 80% of rental income toward qualification
    • Some lenders cap at 4-6 properties; others have no limit

    I’ve structured deals for investors buying their first rental condo in Beltline and for experienced players building 10+ property portfolios. The strategy changes as you scale — so does the lending.

    Mortgage Renewal in Alberta: Don’t Auto-Renew

    If your mortgage is coming up for renewal in 2026 or 2027, do not sign the renewal offer your lender mails you. That offer is almost never their best rate.

    Here’s the play:

    1. Contact a broker 4-6 months before your renewal date
    2. We shop your file across all lenders — including your current one
    3. Use competing offers to negotiate your current lender down
    4. Switch lenders if the math makes sense (most switches cost you nothing — the new lender pays legal and appraisal)

    On a $400,000 renewal, the difference between a posted renewal rate and a broker-negotiated rate can save you $5,000 – $15,000 over the next term.

    First-Time Home Buyer Programs Available in Calgary

    Several programs can help first-time buyers get into the market:

    Federal Programs

    • First Home Savings Account (FHSA): $8,000/year tax-free savings, up to $40,000 lifetime. Deductible contributions + tax-free withdrawals for your first home.
    • Home Buyers’ Plan (HBP): Withdraw up to $60,000 from your RRSP tax-free (repay over 15 years).
    • First-Time Home Buyer Incentive: Shared equity with CMHC (5-10% of purchase price). Use cautiously — it’s not free money.

    Alberta-Specific

    • No provincial first-time buyer program — but the lack of land transfer tax and low property taxes effectively act as your “rebate.”

    FAQ: Calgary Mortgage Questions

    Can I get a mortgage in Calgary if I live in BC?

    Yes. Brokers are licensed provincially but many hold licenses in multiple provinces. I’m licensed through BCFSA and can structure deals for Alberta properties.

    What credit score do I need for a Calgary mortgage?

    Most A-lenders want 680+. With 20%+ down payment, some lenders accept 600+. Below that, B-lenders and private options are available at higher rates.

    How fast can I get a mortgage pre-approval?

    With documents ready, 24-48 hours for a standard pre-approval. For complex files (self-employed, multiple properties), allow 3-5 business days.

    Is it better to go fixed or variable in 2026?

    At current rates, the 5-year fixed offers the best value for most buyers. Variable makes sense if you believe the Bank of Canada will cut further — but the spread is thin right now.

    Can I use rental income to qualify?

    Yes, lenders typically count 50-80% of net rental income. If you’re buying a duplex or legal suite property, that income can significantly boost your purchasing power.

    Ready to Get Started?

    Whether you’re a first-time buyer in Calgary, refinancing an existing property, or building an investment portfolio — the right mortgage structure saves you tens of thousands of dollars.

    I work with clients across Alberta and BC, and I’d be happy to review your situation. No pressure, no obligation — just a straight conversation about your options.

    Get pre-approved in 24 hours: Apply online here

    Or reach out directly:

    • Phone: 604-593-1550
    • Email: varun@kraftmortgages.ca
    • Office: #201-8540 120A St, Surrey, BC V3V 4A4

    Varun Chaudhry is a licensed mortgage broker with BCFSA #M08001935 and President of Kraft Mortgages Canada Inc. This article is for informational purposes and should not be considered financial advice. Rates and terms are subject to change.

  • Calgary Mortgage Broker Guide 2026: Rates, Rules & How to Get the Best Deal

    Calgary skyline with Rocky Mountains at sunset
    Calgary skyline with the Canadian Rockies — Alberta’s largest city and one of Canada’s fastest-growing housing markets.

    Calgary’s housing market doesn’t behave like Toronto or Vancouver. It has its own rhythm — tied to energy prices, migration waves, and a provincial government that deliberately keeps taxes low. If you’re buying a home here, refinancing, or renewing a mortgage in 2026, you need someone who actually understands how Alberta lending works.

    I’m Varun Chaudhry, a licensed mortgage broker based in Surrey, BC. I work with clients across Western Canada, and over the years I’ve structured hundreds of mortgages for Calgary buyers — from first-timers in Tuscany and Evanston to investors eyeing Beltline condos and commercial properties on 17th Ave. Here’s what you need to know about getting a mortgage in Calgary right now.

    What’s Happening with Calgary Real Estate in 2026?

    Calgary saw record migration in 2024-2025, and that wave hasn’t stopped. The city added over 50,000 new residents in 2025 alone, pushing vacancy rates to historic lows and driving prices up across most segments.

    Here’s the current snapshot:

    Calgary Market Snapshot (2026)

    • Average home price: $565,000 – $590,000
    • Detached average: $720,000+
    • Condo average: $335,000 – $360,000
    • Bank of Canada rate: 2.25% (as of early 2026)
    • Best 5-year fixed: ~3.49% – 3.79%
    • Best 5-year variable: ~3.35% – 3.65%

    The key difference from BC and Ontario? No provincial sales tax on resale homes, no land transfer tax, and some of the lowest property taxes in major Canadian cities. That changes the math on affordability significantly.

    Why Use a Mortgage Broker in Calgary Instead of Your Bank?

    I hear this a lot: “My bank gave me a rate, why would I go anywhere else?”

    Here’s why: your bank gives you their rate. A broker shops every lender — banks, credit unions, monoline lenders, trust companies, and private lenders. That competition saves you money.

    In practice, the difference between a bank quote and what a broker can find is typically 0.25% – 0.75% on your rate. On a $500,000 mortgage, that’s $8,000 – $24,000 in interest over a 5-year term. Not pocket change.

    More importantly, a broker structures the deal. If you’re self-employed, have commission income, are buying an investment property, or have any complexity in your file — a bank advisor will often just say no. A broker finds the yes.

    What a Calgary Mortgage Broker Actually Does

    • Shops 30+ lenders to find your best rate and terms
    • Navigates Alberta-specific mortgage rules and exemptions
    • Structures deals for self-employed, new Canadians, and investors
    • Handles the paperwork, appraisals, and lender negotiations
    • Manages timelines so you don’t lose your financing condition

    Alberta Mortgage Rules That Are Different from the Rest of Canada

    If you’re moving from BC or Ontario, pay attention — Alberta has some unique rules that work in your favour:

    1. No Land Transfer Tax

    Ontario and BC charge land transfer tax on every purchase. In Calgary, you pay zero. On a $600,000 home, that’s $8,000 – $12,000 you keep in your pocket compared to buying in Vancouver or Toronto.

    2. No Provincial Sales Tax on Resale Homes

    GST applies to new builds only. Resale homes are GST-exempt. Simple.

    3. Lower Property Taxes

    Calgary’s property tax rate is roughly 0.55% – 0.65% of assessed value. Compare that to Toronto (~0.63%) or Vancouver (~0.30% but with much higher home prices). On a $600,000 home, expect around $3,500 – $4,000/year in Calgary.

    4. Alberta Mortgage Default Rules

    Alberta has a unique remedy on default provision that can affect foreclosure timelines. Lenders take this into account when underwriting — it’s one reason some lenders have slightly different criteria for Alberta properties.

    Current Mortgage Rates in Calgary (May 2026)

    Rates move daily, but here’s a realistic range for well-qualified borrowers:

    Current Calgary Mortgage Rates

    • 1-year fixed: 4.49% – 4.79%  |  Variable: 4.29% – 4.59%
    • 2-year fixed: 3.99% – 4.29%  |  Variable: 3.79% – 4.09%
    • 3-year fixed: 3.69% – 3.99%  |  Variable: 3.49% – 3.79%
    • 5-year fixed: 3.49% – 3.79%  |  Variable: 3.35% – 3.65%

    Note: These are broker-access rates. Bank-posted rates are typically higher. Individual rate depends on credit score, down payment, income, and property type.

    With the Bank of Canada rate at 2.25% and economists split on further cuts, the 5-year fixed is the sweet spot for most Calgary buyers right now — you lock in a competitive rate without betting on continued cuts.

    Young couple buying their first home in Calgary Alberta

    How Much House Can You Afford in Calgary?

    Let’s run some real numbers. The mortgage stress test still applies — you qualify at the Bank of Canada qualifying rate or your contract rate + 2%, whichever is higher.

    Example: First-Time Buyer, $120K Household Income

    • Purchase price: $560,000
    • Down payment (5%): $28,000
    • Mortgage amount: $532,000
    • Monthly payment (5yr @ 3.59%): $2,670/mo
    • Property tax (est.): $310/mo
    • Heat/utilities: $200/mo
    • Total monthly housing cost: ~$3,180

    At $120K income, your gross monthly is $10,000. Housing at $3,180 is roughly 32% GDS — well within the 39% threshold. That’s a comfortable buy in a Calgary neighbourhood like Nolan Hill, Redstone, or Auburn Bay.

    Calgary Neighbourhoods Worth Watching in 2026

    Where you buy matters as much as what you pay. Here are areas with strong appreciation potential:

    North Calgary

    • Evanston / Sage Hill / Nolan Hill: Established family communities, good schools, $500K – $700K detached
    • Livingston / Cornerstone: Newer builds, still developing amenities, $480K – $620K

    South Calgary

    • Auburn Bay / Cranston: Lake community appeal, $550K – $800K
    • Seton: Calgary’s newest urban hub, South Health Campus, mixed residential

    Inner City / Beltline

    • Beltline / Mission / Kensington: Condo-heavy, strong rental demand, $300K – $500K
    • Inglewood / East Village: Revitalization plays, mixed-use growth

    West Calgary

    • Varsity / Dalhousie / Brentwood: Established, close to U of C, strong resale
    • Tuscany / Royal Oak: Family-friendly, mountain views, $550K – $750K

    Self-Employed? Here’s How to Get a Mortgage in Calgary

    Alberta has one of the highest self-employment rates in Canada — especially in Calgary’s energy, tech, and professional services sectors. The challenge? Lenders don’t love variable income.

    What You’ll Need

    • 2 years of T1 Generals with Notice of Assessment
    • 12 months of business bank statements
    • GST/HST returns (3 years if applicable)
    • Financial statements if incorporated
    • A broker who knows how to present your file (this matters more than the documents)

    Some lenders use stated income programs for self-employed borrowers, which can be a lifeline if your tax returns don’t reflect your actual earning power. Not every broker knows these programs — make sure yours does.

    Investment Properties in Calgary: What You Need to Know

    Calgary’s rental market is tight. Vacancy rates are under 3%, and rents have climbed 15-20% since 2023. That makes investment properties attractive — but the lending rules are different.

    Key Differences for Investment Mortgages

    • Minimum 20% down payment (no CMHC insurance on rentals)
    • Rates are typically 0.25% – 0.50% higher than owner-occupied
    • Lenders count 50% – 80% of rental income toward qualification
    • Some lenders cap at 4-6 properties; others have no limit

    I’ve structured deals for investors buying their first rental condo in Beltline and for experienced players building 10+ property portfolios. The strategy changes as you scale — so does the lending.

    Mortgage Renewal in Alberta: Don’t Auto-Renew

    If your mortgage is coming up for renewal in 2026 or 2027, do not sign the renewal offer your lender mails you. That offer is almost never their best rate.

    Here’s the play:

    1. Contact a broker 4-6 months before your renewal date
    2. We shop your file across all lenders — including your current one
    3. Use competing offers to negotiate your current lender down
    4. Switch lenders if the math makes sense (most switches cost you nothing — the new lender pays legal and appraisal)

    On a $400,000 renewal, the difference between a posted renewal rate and a broker-negotiated rate can save you $5,000 – $15,000 over the next term.

    First-Time Home Buyer Programs Available in Calgary

    Several programs can help first-time buyers get into the market:

    Federal Programs

    • First Home Savings Account (FHSA): $8,000/year tax-free savings, up to $40,000 lifetime. Deductible contributions + tax-free withdrawals for your first home.
    • Home Buyers’ Plan (HBP): Withdraw up to $60,000 from your RRSP tax-free (repay over 15 years).
    • First-Time Home Buyer Incentive: Shared equity with CMHC (5-10% of purchase price). Use cautiously — it’s not free money.

    Alberta-Specific

    No provincial first-time buyer program — but the lack of land transfer tax and low property taxes effectively act as your rebate.

    READY TO BUY IN CALGARY?

    Speak with a licensed mortgage broker about your options

    Book Free Consult →
    Apply Now

    FAQ: Calgary Mortgage Questions

    Can I get a mortgage in Calgary if I live in BC?

    Yes. Brokers are licensed provincially but many hold licenses in multiple provinces. I’m licensed through BCFSA and can structure deals for Alberta properties.

    What credit score do I need for a Calgary mortgage?

    Most A-lenders want 680+. With 20%+ down payment, some lenders accept 600+. Below that, B-lenders and private options are available at higher rates.

    How fast can I get a mortgage pre-approval?

    With documents ready, 24-48 hours for a standard pre-approval. For complex files (self-employed, multiple properties), allow 3-5 business days.

    Is it better to go fixed or variable in 2026?

    At current rates, the 5-year fixed offers the best value for most buyers. Variable makes sense if you believe the Bank of Canada will cut further — but the spread is thin right now.

    Can I use rental income to qualify?

    Yes, lenders typically count 50-80% of net rental income. If you’re buying a duplex or legal suite property, that income can significantly boost your purchasing power.

    Ready to Get Started?

    Whether you’re a first-time buyer in Calgary, refinancing an existing property, or building an investment portfolio — the right mortgage structure saves you tens of thousands of dollars.

    I work with clients across Alberta and BC, and I’d be happy to review your situation. No pressure, no obligation — just a straight conversation about your options.

    GET PRE-APPROVED IN 24 HOURS

    Start your Calgary mortgage application today

    Apply Online →
    Call 604-593-1550

    Or reach out directly:

    • Phone: 604-593-1550
    • Email: varun@kraftmortgages.ca
    • Office: #201-8540 120A St, Surrey, BC V3V 4A4

    Varun Chaudhry is a licensed mortgage broker with BCFSA #M08001935 and President of Kraft Mortgages Canada Inc. This article is for informational purposes and should not be considered financial advice. Rates and terms are subject to change.

  • How the Mortgage Stress Test Works in BC (2026): Complete Guide

    How the Mortgage Stress Test Works in BC (2026): Complete Guide

    How the Mortgage Stress Test Works in BC (2026): A Complete Guide for Buyers and Renewers

    Target Keyword: mortgage stress test BC 2026

    The mortgage stress test is a federal qualification requirement that ensures borrowers can afford their mortgage payments at a higher interest rate than their actual contracted rate. As of April 2026, the minimum qualifying rate is 5.5% or your contracted rate plus 2% — whichever is higher. This applies to both insured and uninsured mortgages in British Columbia, affecting first-time buyers, repeat purchasers, and anyone switching lenders at renewal.

    What Is the Mortgage Stress Test?

    Introduced by the Office of the Superintendent of Financial Institutions (OSFI) in 2018 and updated by the federal government in 2024, the mortgage stress test requires lenders to verify that borrowers can manage payments at a qualifying rate higher than what they’ll actually pay. It’s not a separate application — it’s built into every mortgage approval calculation at federally regulated lenders.

    The stress test applies to:

    • New purchases — all mortgages with less than 20% down (insured) and many with 20%+ down (uninsured) at federally regulated lenders
    • Refinances — yes, the stress test applies when you refinance with a new lender
    • Switching lenders at renewal — if your term ends and you want a better rate elsewhere, the stress test applies at the new lender
    • Private and equity lenders — generally exempt, as they operate outside federal regulation

    Key Takeaways

    • The qualifying rate is 5.5% or your contracted rate + 2%, whichever is higher
    • Stress test applies at purchase, refinance, and lender switches — not when staying with your current lender at renewal
    • It reduces your maximum purchase price by roughly 15–20% compared to pre-stress-test math
    • Private and equity lenders are exempt — a significant advantage for borrowers who don’t qualify under stress test rules
    • The Bank of Canada’s overnight rate (currently 2.75% as of April 2026) doesn’t directly set the stress test floor

    The 2026 Stress Test Rules: How It’s Calculated

    The stress test formula is straightforward but has a big impact on your borrowing power:

    Step 1: Determine Your Qualifying Rate

    Your lender takes the higher of:

    • The Bank of Canada’s 5-year benchmark rate (currently 5.5%)
    • Your contracted mortgage rate plus 2%

    Step 2: Calculate the Monthly Payment at the Qualifying Rate

    Your lender runs a mortgage payment calculation using the qualifying rate (not your actual rate), your amortization, and the loan amount.

    Step 3: Apply the Standard Affordability Ratios

    Using the higher (stressed) payment, your lender checks:

    • GDS (Gross Debt Service): Must not exceed 39%. Calculated as (monthly housing costs) ÷ (gross monthly income) × 100. Housing costs include mortgage payment, property tax, heating, and 50% of condo fees.
    • TDS (Total Debt Service): Must not exceed 44%. Adds all other debt payments (car loans, credit cards, lines of credit) to the housing costs before dividing by income.

    Example: How the Stress Test Reduces Your Budget

    Let’s say you’re buying a $800,000 home in Surrey with 10% down ($720,000 mortgage), 25-year amortization, $120,000 gross household income, and $500/month in other debts.

    Without stress test (at contracted rate of 4.39%):

    • Monthly payment: ~$3,950
    • GDS: ~39.5% — borderline

    With stress test (at qualifying rate of 6.39%):

    • Monthly payment: ~$4,780
    • GDS: ~47.8% — fails the 39% threshold

    In this scenario, the stress test could reduce your maximum purchase price from $800,000 to roughly $650,000–$680,000. That’s a $120,000–$150,000 difference in Surrey’s competitive market.

    Who Is Exempt from the Stress Test?

    Not every borrower faces the stress test. Here’s who can sidestep it:

    • Borrowers staying with their existing lender at renewal: If you don’t switch lenders, no stress test reassessment is required — though your lender will still confirm you can afford payments
    • Private and equity lenders: Institutional equity lenders (like Antrim, Vault, Sequence Capital) and private lenders operate outside federal regulation and don’t apply the stress test. They assess affordability differently — primarily through property equity and loan-to-value ratio
    • Provincially regulated credit unions in BC: Some BC credit unions set their own qualifying standards, though most follow OSFI guidelines voluntarily
    • Assumption of existing mortgages: Taking over a vendor’s existing mortgage may avoid the stress test, depending on the lender

    Broker Field Notes

    In practice, the stress test hits self-employed borrowers and commission earners hardest. Their stated income may look lower on paper, so the GDS/TDS ratios become very tight. This is where equity lending becomes a real option — if you have strong property equity (65% LTV or better), an institutional equity lender can qualify you based on the asset, not your income documentation. We see this frequently with Surrey business owners who have $500K+ in home equity but complex tax returns.

    Strategies to Pass the Stress Test

    1. Increase Your Down Payment

    A larger down payment means a smaller mortgage, which means a lower stressed monthly payment. Every extra $50,000 down can increase your qualifying purchase price by approximately $40,000–$50,000 once the stress test math is applied.

    2. Pay Down Existing Debt

    Reducing your TDS is often faster than increasing income. Paying off a $15,000 car loan could improve your TDS by 3–5 percentage points — potentially the difference between qualifying and not.

    3. Add a Co-Signer or Co-Borrower

    Adding a spouse or family member with income combines your qualifying power. Both incomes are stress-tested, but the higher combined income can absorb the higher payment.

    4. Consider a Shorter-Term Fixed Rate to Build History

    Some borrowers use a 1–2 year term with a B-lender or equity lender, build 12–24 months of perfect payment history, and then refinance to an A-lender. The payment history strengthens the file even though the stress test math doesn’t change.

    5. Look at Alternative Lending Channels

    If the stress test is the only barrier and you have strong equity, institutional equity lenders offer rates significantly below individual private lenders while avoiding stress test requirements entirely.

    Stress Test and Mortgage Renewals: What BC Homeowners Need to Know

    One of the most common misunderstandings about the stress test involves renewals. Here’s the rule:

    Renewing with your current lender? No stress test. Your lender sends a renewal offer, you sign, done.

    Switching to a new lender at renewal? Yes, stress test applies. The new lender must qualify you at the current stress test rate, even though you’ve been making payments for years without issue.

    This catches many BC homeowners off guard. If rates have risen since your original purchase, the stress test qualifying rate is higher now than when you first qualified — meaning you might not pass the same stress test that approved your original mortgage.

    RENEWING SOON AND WANT TO COMPARE RATES?

    Speak with a licensed BC mortgage broker about your renewal options

    Book Free Consult →
    Apply Now

    Stress Test vs. Actual Affordability: The Real-World Gap

    The stress test is a blunt instrument. It uses the same GDS/TDS thresholds for a $400,000 condo in Abbotsford as it does for a $1.8 million house in Vancouver. It doesn’t account for:

    • Regional cost-of-living differences within BC
    • Household savings and net worth
    • Future income growth (common for early-career professionals)
    • Prepayment flexibility that most Canadian mortgages offer

    CMHC and the federal government have discussed regional stress test adjustments, but as of April 2026, no changes have been implemented. The qualifying rate remains a national standard.

    First-Time Buyers: Stress Test Survival Guide

    For first-time buyers in BC’s high-priced markets, the stress test can be the biggest barrier — not the down payment. Here’s a practical approach:

    1. Get pre-approved first — a mortgage broker runs the stress test calculation and tells you exactly what you qualify for. This sets your search budget.
    2. Factor in the stress test reduction — your maximum purchase price will be lower than a simple online calculator suggests. Budget for the reality.
    3. Consider the First Home Savings Account (FHSA) — up to $8,000/year in tax-deductible contributions, up to $40,000 lifetime, for your down payment.
    4. Don’t max out your GDS/TDS — qualifying at 38.9% GDS leaves zero buffer for rate increases, job changes, or unexpected expenses. Aim for 30–32% GDS if possible.
    5. Explore alternative paths — if A-lending doesn’t work, institutional equity lending can bridge the gap while you build a stronger file for refinancing later.

    Frequently Asked Questions

    What is the minimum stress test rate in Canada for 2026?

    The minimum qualifying rate is 5.5% or your contracted mortgage rate plus 2%, whichever is higher. This rate is set by the federal government and applies nationwide.

    Does the stress test apply to mortgage renewals in BC?

    Only if you switch lenders. If you renew with your existing lender, the stress test does not apply. If you want to shop for a better rate at a different lender, you must re-qualify under current stress test rules.

    Can I bypass the stress test with a private lender?

    Yes. Private lenders and institutional equity lenders are not federally regulated and do not apply the stress test. They assess borrowers primarily on property equity and loan-to-value ratio. However, their rates are typically higher than A-lender rates.

    How much does the stress test reduce my borrowing power?

    For most borrowers, the stress test reduces maximum purchase price by 15–20% compared to what they’d qualify for without it. The exact reduction depends on your income, down payment, debts, and current mortgage rates.

    Does the stress test apply to refinancing?

    Yes. When you refinance with any federally regulated lender, you must pass the stress test at the current qualifying rate, even if you’re just accessing home equity and not increasing your loan balance significantly.

    What’s the difference between the stress test and my actual mortgage rate?

    Your actual mortgage rate is what you pay each month. The stress test rate is a hypothetical higher rate used only to verify you could handle payments if rates rise. It’s a safety check, not your actual cost.

    Do BC credit unions use the stress test?

    Most BC credit unions follow OSFI stress test guidelines voluntarily, even though they’re provincially regulated. Some may have internal qualifying standards that differ slightly. Check with your specific credit union.

    What if I fail the stress test but have excellent credit?

    Credit score doesn’t directly affect the stress test math — it’s about income ratios. If you fail the stress test, options include increasing your down payment, reducing debt, adding a co-borrower, or working with an equity lender who doesn’t use stress test qualification.

    Does the stress test apply to investment properties?

    Yes, and it can be more restrictive. Lenders often use a higher GDS/TDS threshold for rental properties and may only count 50% of rental income toward qualifying. The stress test still applies at the full qualifying rate.

    Can I get a stress test pre-approval before house hunting?

    Absolutely — and you should. A licensed mortgage broker can run a full stress test calculation and provide a pre-approval letter showing your maximum qualifying purchase price. This prevents disappointment after finding a home you can’t qualify for.

    NOT SURE HOW THE STRESS TEST AFFECTS YOU?

    Get a free stress test assessment from a licensed BC mortgage broker

    Book Free Consult →
    Apply Now

  • Vancouver Mortgage Broker Guide: Best Rates & Local Expertise 2026

    Vancouver Mortgage Broker Guide: Best Rates & Local Expertise 2026

    Buying a home in Vancouver is competitive. Always has been. The difference now? Rates are finally coming down from the 2023-2024 highs, and buyers who’ve been sitting on the sidelines are jumping back in. But the market hasn’t gotten any simpler — especially when you’re trying to figure out which lender, what rate, and how much you actually qualify for.

    I’m Varun Chaudhry. I run Kraft Mortgages out of Surrey, and I’ve been brokering deals across the Lower Mainland for over 23 years. A big chunk of my clients live or buy in Vancouver proper. This guide covers what I tell them — straight up, no fluff.

    Where Vancouver Mortgage Rates Sit in 2026

    As of spring 2026, here’s what you’re looking at for qualified buyers with decent credit and provable income:

    • 5-year fixed: roughly 4.5% to 5.2%
    • 5-year variable: around 5.0% to 5.7%
    • 3-year fixed: 4.3% to 4.9%
    • 1-year fixed: 4.1% to 4.6%

    These aren’t the posted bank rates — those sit a full percentage point higher. What you see above is what a good broker can actually negotiate. The gap between bank-posted and broker-accessible rates is why brokers exist, and it’s why roughly 40% of Canadian mortgages now go through one.

    Should you lock fixed or go variable? Depends on your stomach. Fixed gives you certainty. Variable gives you flexibility and usually costs less if you’re planning to break the mortgage early (variable penalties are typically just three months’ interest, while fixed penalties can be massive). For most Vancouver buyers I work with, the 5-year fixed at around 4.7-4.9% is the sweet spot.

    Vancouver Neighbourhoods: What You’re Actually Buying Into

    Vancouver isn’t one market. It’s a dozen micro-markets glued together, and lenders treat them differently too. Here’s how it shakes out for financing:

    Kitsilano

    Still one of the most sought-after neighbourhoods in the city. Detached homes here regularly trade above $3 million, and even a one-bedroom condo will run you $650,000+. The good news: lenders love Kits. High property values, strong resale, low default risk. If you’ve got the down payment, financing is straightforward.

    Mount Pleasant

    This area’s been on a tear for years. Condos dominate, with plenty of new builds along the Broadway corridor. Typical condo price: $550K to $750K. Lenders are comfortable here, but if you’re buying into a newer building, make sure it’s on the MLI Select approved list — more on that later.

    East Van (Grandview-Woodland, Strathcona)

    East Van’s come a long way. Character homes on tree-lined streets, townhouse developments, and a growing condo market. Prices are more accessible — detached homes in the $1.6-2.2M range, condos from $450K. The neighbourhood’s still got rough edges that some conservative lenders don’t love, but most A-lenders will fund here without blinking.

    Downtown and Yaletown

    Condo territory. Lots of investors, lots of pre-sales. If you’re buying to live here, great — standard financing applies. If you’re buying as an investment, lenders will look harder at your income, existing portfolio, and the building’s rental financials. Expect to put down at least 20% on a rental property, and some lenders now want 25% in this market.

    Kerrisdale

    More detached homes, mature trees, established families. House prices sit comfortably in the $2.5-4M range. The lending conversation here is usually about how to structure the mortgage on a high-value property — often a combination of first mortgage and a home equity line of credit for renovation capital.

    Commercial Drive

    The Drive’s got personality. Older condos, duplexes, some detached character homes. Prices are gentler — you can still find a condo under $500K if you look. Lenders sometimes flag older buildings (pre-1990) for additional scrutiny around plumbing and envelope condition, so budget for a good inspection.

    Real Client Stories (Names Changed)

    Raj and Priya — First-Time Buyers in Mount Pleasant

    Raj’s a software developer making $120K. Priya works in healthcare, $85K. Combined income of $205K, solid. They’d saved $120K for a down payment and had their hearts set on a 2-bedroom condo near Broadway and Main — listed at $680,000.

    They went to their bank first. The bank offered them a 5-year fixed at 5.15% with a $3,500 cash back promotion that sounded great until we did the math. I shopped their file to 12 lenders and found a 5-year fixed at 4.62% through a monoline lender. Over five years, that saved them roughly $14,200 in interest — more than four times the bank’s cash back offer.

    We got them pre-approved in 48 hours. Their offer was accepted, and they closed in six weeks. They’re now paying $3,180/month instead of the $3,440 the bank quoted.

    Mike — Rental Property in East Van

    Mike already owned a condo in Burnaby (mortgaged, $480K remaining) and wanted to pick up a pre-sale townhouse in East Van for $725,000. His bank said no — they didn’t like that his debt service ratios were too tight with the existing mortgage.

    We went a different route. I found a lender who’d count 80% of the rental income from his existing Burnaby unit (some lenders only count 50%), which freed up enough room in his ratios. We structured the new mortgage at 4.85% fixed for five years with a 25% down payment. The deal closed in March 2026. Mike’s tenants cover both mortgage payments and he clears about $400/month net.

    Susan — Refinancing a Kerrisdale Home

    Susan bought her Kerrisdale house in 2015 for $1.8 million. It’s now worth around $3.1 million, and her mortgage balance was down to $680,000. She wanted to pull out $400,000 to renovate the kitchen and add a laneway house.

    We did a straight refinance at 4.55%, bringing her total mortgage to $1.08 million — still under 35% loan-to-value. The laneway house, once built, will generate $2,000-2,500/month in rental income and add roughly $300-400K to her property value. Clean deal, strong equity position, and every lender we approached wanted it.

    Vancouver residential neighbourhood street scene
    Vancouver neighbourhoods each come with their own financing considerations

    Why Use a Mortgage Broker Instead of Going Direct

    I get it. You’ve banked with the same institution for years. They know your name. It feels easy to just walk in and ask for a mortgage. Here’s what they won’t tell you:

    Your bank shows you one rate. Their rate. I show you rates from 30+ lenders — big banks, monoline lenders, credit unions, and private lenders. On a $700,000 mortgage, even a 0.3% difference in rate saves you $6,300 over five years.

    Your bank’s advisor is an employee. They’re selling their employer’s products. I’m independent. My job is to find the best deal for you, not to hit a quota for RBC or TD.

    Your bank doesn’t know every lender. There are excellent monoline lenders (Meridian, Motusbank, First National, Equitable Bank) that only work through brokers. These lenders often have sharper rates because they don’t have the overhead of a branch network. Your bank rep literally cannot offer you their products.

    My service is free to you. Lenders pay broker commissions, not borrowers. You pay exactly the same rate whether you come through me or go direct — except I usually find you a better rate. There is no catch.

    I handle the paperwork. If you’ve ever applied for a mortgage at a bank, you know the drill — forms, more forms, follow-up calls, missing documents, “just one more thing.” I manage all of that. One application, one set of documents, and I do the running around.

    The Vancouver Home Buying Process, Step by Step

    Step 1: Get Pre-Approved

    Don’t start browsing open houses without a pre-approval. In Vancouver, you’ll need to move fast when you find the right place, and sellers won’t take your offer seriously without financing in place. A pre-approval locks your rate for 90-120 days and tells you exactly what you can afford. Takes us about 48 hours.

    Step 2: Know Your Budget

    Pre-approval tells you what a lender will fund. Your actual budget should account for closing costs (property transfer tax in Vancouver can be steep — 1% on the first $200K, 2% up to $2M, and 3% above that), moving expenses, and a cushion. Don’t max out your approval.

    Step 3: Find Your Place

    Work with a realtor who knows the neighbourhood you want. They’ll set you up on auto-searches and get you into properties as soon as they list. In a competitive market, being first matters.

    Step 4: Make an Offer

    Your realtor handles this, but here’s where having a broker helps: if the seller wants a quick close, or there’s a subject-free angle, I can often accelerate the financing timeline by working directly with underwriters. Banks can’t always do that.

    Step 5: Fulfill Subjects

    Typical subjects in Vancouver: financing, inspection, and sometimes strata documents if you’re buying a condo. I handle the financing side. Give me the accepted contract and I’ll have full approval within 3-5 business days.

    Step 6: Close

    Your lawyer or notary handles the actual closing. I send them the mortgage instructions, you sign, and you get the keys. The whole process from offer to possession usually takes 30-60 days.

    Condo vs. House: The Financing Differences in Vancouver

    This trips up more Vancouver buyers than almost anything else.

    Condos

    When you buy a condo, the lender is underwriting the building as much as they’re underwriting you. They want to know: Is the building well-maintained? Is the strata financially healthy? Are there any pending special assessments? How many units are owner-occupied versus rented out?

    The MLI Select program matters here. If the building is on the MLI Select list (formerly the CMHC condo list), it’s been pre-screened and most lenders will finance it smoothly. If it’s not on the list, some lenders won’t touch it, and others will require additional documentation or charge a premium rate.

    Condos under $500K and 600 sq ft or less can also face insurance challenges. Many lenders require full replacement cost coverage, and some older or smaller Vancouver buildings struggle to get it.

    Houses

    Detached homes are simpler on the lending side because there’s no strata to worry about. The main considerations are property value, your income, and the size of your down payment. That said, in Vancouver’s price range ($1.5M+ for most detached homes), you’re looking at jumbo mortgage territory, and not all lenders go that high.

    For houses, I often suggest splitting the financing: a first mortgage up to 80% of value at the best rate, plus a home equity line of credit for flexibility. It keeps your monthly payments lower and gives you access to capital for renos or investments without having to refinance.

    What Makes a Good Vancouver Mortgage Broker

    Experience matters, and not the “I’ve been doing this for two years” kind. Vancouver’s market is complex. Strata financing, pre-sales, assignments, investment properties, foreign buyer rules (even though the ban has been lifted, some lenders still have their own policies), high-ratio mortgage insurance through CMHC or Sagen — you want someone who’s dealt with all of it.

    I’ve been licensed since 2003. I’ve seen the 2008 crash, the 2016-2018 boom, the rate hikes of 2022-2023, and the recovery happening right now. My office is in Surrey, but I work with Vancouver clients every single week. The Lower Mainland is my market, and I know it cold.

    What you should expect from your broker:

    • Same-day response to messages during business hours
    • Clear explanation of rates, terms, and why they’re recommending a specific lender
    • Access to both A-lenders (banks, monolines) and B/private lenders for tougher files
    • Honesty about what you can and can’t afford — I won’t put you in a mortgage that’s going to stress you out
    • Post-closing support — rate renewals, refinancing questions, everything

    If your broker isn’t doing these things, find one who will. There’s no shortage of us in BC.

    Getting Started

    If you’re looking to buy in Vancouver this year, the smartest thing you can do right now is get pre-approved. Rates are moving, the spring market is active, and being ready to make an offer separates the buyers who get homes from the ones who keep watching from the sidelines.

    Reach out through our residential mortgage page, or if you’re in the Surrey/Vancouver area, give me a call. We’ll figure out what you qualify for, what your options are, and get you on the path to homeownership.

    — Varun Chaudhry, Licensed Mortgage Broker, BCFSA #M08001935

    Frequently Asked Questions

    How much does a mortgage broker charge in Vancouver?

    Nothing to the borrower for standard A-lender deals. The lender pays the commission. For private or B-lender deals, there may be a broker fee (typically 1-2% of the mortgage amount), but I’ll always disclose that upfront before you commit to anything.

    How long does mortgage pre-approval take?

    Usually 24 to 48 hours once I have your documents: two years of T4s or tax returns, recent pay stubs, a recent bank statement showing your down payment, and an idea of what you’re looking to buy. That’s it.

    Can I get a mortgage with less than 20% down in Vancouver?

    Yes. Anything under 20% down requires mortgage default insurance through CMHC, Sagen, or Canada Guaranty. The premium gets added to your mortgage balance. For purchases under $1 million, this is straightforward. For purchases over $1 million, you need at least 20% down — no exceptions.

    What’s the minimum credit score for a mortgage in Vancouver?

    For A-lender approval, you generally need a beacon score of 650 or higher. Some lenders will go to 620 with compensating factors. Below 600, we’re looking at alternative lenders with higher rates but more flexible qualification criteria. I work with all of them.

    Is it better to go fixed or variable in 2026?

    With the Bank of Canada having cut rates and more cuts expected, variable has appeal. But the spread between fixed and variable is narrow right now. For most buyers, the 5-year fixed around 4.7-4.9% offers the best balance of rate and peace of mind. If you plan to sell or refinance within 2-3 years, variable may save you on prepayment penalties.

    Do you work with first-time home buyers?

    A lot of my clients are first-timers. I walk you through the whole process — from figuring out what you can afford to explaining every line of your mortgage commitment. No dumb questions. Ever.

    What’s the property transfer tax in Vancouver?

    For residential properties: 1% on the first $200,000, 2% on the balance up to $2 million, and 3% on anything above $2 million. First-time home buyers may be eligible for an exemption if the property is under $575,000 (partial exemption up to $625,000).

    Can I use a mortgage broker if I’m self-employed?

    Absolutely. Self-employed borrowers are a big part of my practice. We can use stated income programs or your Notice of Assessment to qualify. If your business is newer or your tax returns show lower income (because you’ve written off expenses — smart, but it makes traditional qualification harder), I have lenders who understand that.

  • How to Get a Mortgage When Self-Employed in BC (Complete Guide 2026)

    How to Get a Mortgage When Self-Employed in BC (Complete Guide 2026)

    Self-Employed Mortgage BC: Why It’s Harder (But Not Impossible)

    I’ve been a mortgage broker in Surrey for over 23 years. If there’s one question I hear more than any other from self-employed clients, it’s this: “Why is it so much harder for me to get a mortgage than my W-2 friends?”

    The honest answer? Canadian banks built their underwriting systems around T4 employees. They want to see a neat line on your T1 General showing exactly what you earned. They want a T4 slip. They want an employment letter from someone else — proof that your income is stable and verifiable.

    When you run your own business, your income looks messy on paper. You’ve got write-offs. You have good years and lean years. You might pay yourself through dividends or leave money in your corporation instead of taking a salary. All of that makes perfect business sense — and it drives bank underwriters absolutely nuts.

    But here’s what most people don’t know: there are lenders who actually prefer self-employed borrowers. You just need to know where to look and what to bring to the table. That’s what this guide is about.

    What Lenders Actually Look For

    Before we get into the specific programs, let’s talk about what any lender — whether it’s RBC or a private mortgage fund — is trying to figure out when they look at your file.

    The Three Questions Every Lender Asks

    1. Can this person make the payments? — That’s your debt service ratios (GDS and TDS). They want your housing costs plus debt payments to stay within certain thresholds.
    2. What happens if they can’t? — That’s your equity position. The bigger the down payment, the less the lender worries about a default eating into their principal.
    3. Is this borrower a good risk? — Credit history, employment history, asset base. They’re looking for patterns, not perfection.

    Self-employed borrowers often stumble on question one because their income looks low on paper. That’s the whole problem. But if you’re strong on questions two and three, you’ve still got options — and good ones.

    The Document Checklist: What You Actually Need

    Every lender is going to ask for some combination of the following. The sooner you gather this stuff, the faster your application moves.

    For A-Lenders (Big Banks and Monoline Lenders)

    • 2 years of T1 Generals (personal) — both pages, signed
    • Notice of Assessment (NOA) from CRA for the past 2 years
    • Articles of Incorporation (if incorporated) or master business licence (if sole prop)
    • HST/GST returns — sometimes 12 months, sometimes 2 years depending on the lender
    • Financial statements — if you’re incorporated, they’ll want the corporate T2 as well
    • Bank statements — typically 3 months, showing your business or personal deposits
    • Void cheque or pre-authorized debit form for the mortgage payment

    For B-Lenders and Private Lenders

    • 2 years of T1 Generals and NOAs still preferred but not always required
    • Bank statements showing you can service the debt (3-6 months)
    • Appraisal of the property
    • Credit report (we pull this)
    • Sometimes a letter from your accountant confirming you’re operating and profitable

    See the difference? B-lenders and private lenders care more about the property and your cash flow than they do about your tax returns. That flexibility comes at a cost (higher rates), but it’s the reason self-employed borrowers in BC have real options.

    The Main Paths to a Mortgage When You’re Self-Employed

    Path 1: Conventional A-Lender Approval

    If you’ve been self-employed for 2+ years and your T1 Generals show a reasonable income, you can qualify through the big banks or monoline lenders just like any salaried borrower. Your line 150 (net income) is what they use. If you write off a ton of expenses and your net income looks tiny, this path might not work — but it’s always worth checking first.

    Current rate range (as of April 2026): 4.89% – 5.49% for 5-year fixed

    This is the cheapest route. If you can go here, go here.

    Path 2: Stated Income Programs (The Game Changer)

    This is where things get interesting for self-employed borrowers. Several B-lenders in Canada offer “stated income” or “stated income plus” programs. Here’s how they work:

    Instead of proving your income with tax returns, you state what you earn, and the lender uses that figure for qualifying purposes. You still need to show you’ve been self-employed for a minimum period (usually 2 years), and they’ll want to see that your business is real — incorporation docs, GST/HST numbers, bank statements with business deposits.

    They’re not going to let you claim $300K if your bank account shows $4K/month in deposits. The stated income needs to be reasonable for your industry and your history. But within that guardrail, there’s flexibility that doesn’t exist at the A-lender level.

    Current rate range (as of April 2026): 6.49% – 7.99% for 5-year fixed, depending on the lender, LTV, and credit profile

    Lenders that offer stated income programs in BC include Home Trust, Equitable Bank, MCAP, and several others that work through the broker channel. These are not fly-by-night operations — Home Trust alone funds billions in mortgages annually. They’ve been around for decades.

    Path 3: Business for Self (BFS) Programs

    “Business for Self” is lender terminology for self-employed borrowers who don’t fit the standard income verification model. It’s not the same as stated income — BFS programs generally use a different qualifying method instead of letting you pick a number.

    Common approaches include:

    • Averaging your last 2 years of net income — this helps if you had one great year and one weaker year
    • Adding back certain write-offs — some lenders will add back business-use-of-home, vehicle expenses, and depreciation to bump up your qualifying income
    • Using gross revenue — a few lenders will look at your top-line revenue and apply a percentage (e.g., 15-20%) as your qualifying income

    Each lender has their own formula. Part of what I do is match you with the lender whose formula works best for your specific tax situation. Sometimes the difference between an approval and a decline is just picking the right lender.

    Path 4: Private Mortgage Lenders

    When A-lenders and B-lenders both say no — maybe your credit took a hit, or you’ve only been self-employed for a year, or you’re buying a property that’s a bit unusual — private lenders step in.

    Private mortgages are asset-based. The lender cares primarily about the property value and your equity. If you’re putting 25-35% down on a purchase or have that much equity in a refinance, a private lender will almost always say yes. Approval can happen in 24-48 hours. Funding in a week or two.

    Current rate range (as of April 2026): 9.99% – 14.99%, plus lender and broker fees

    Yes, it’s expensive. But here’s how I explain it to clients: private mortgages are a bridge, not a destination. You use a private lender for 12-24 months while you clean up whatever the issue is — build up your income history, fix your credit, get your corporate returns filed — then refinance into a B-lender or A-lender at a much lower rate.

    Real Client Scenarios (Names Changed)

    Scenario 1: Raj — Trucking Company Owner, Surrey

    Raj runs a small fleet of five trucks in the Fraser Valley. He’d been incorporated for four years and wanted to buy a home for his family — budget around $950K. The problem: his accountant was aggressive with write-offs. His T1 Generals showed $65K net income, which wasn’t enough to qualify at any A-lender for the mortgage he needed.

    We went with a stated income program through Home Trust. Based on his bank statements and business revenue, we stated his income at $140K — reasonable for a five-truck operation. At a 6.89% rate on a 5-year fixed, his payment was around $4,900/month. He had 20% down from savings built up over years of running his business.

    Approval took 3 business days. He closed in 3 weeks.

    Scenario 2: Priya — Real Estate Agent, Vancouver

    Priya’s been selling real estate in Vancouver for seven years. Her income is highly variable — $180K in 2023, $95K in 2024 (a slow market year), and she was on track for $210K in 2025. She wanted to refinance her condo to pull out equity for another investment property.

    Her bank averaged her two most recent T1s at $137.5K and said that wasn’t enough for the additional borrowing she wanted. We took her file to Equitable Bank, which offered a BFS program that added back her vehicle lease, home office expenses, and marketing costs. That bumped her qualifying income to $168K — enough for the refinance she needed.

    Rate: 6.29% on a 3-year fixed. She was happy. The add-backs made all the difference.

    Scenario 3: Mike — New Contractor, Langley

    Mike left his carpentry job in early 2025 to start his own renovation company. By late 2025, he had a solid book of business and wanted to buy a house in Langley for his family. The issue: he’d only been self-employed for about 10 months. No lender was going to approve him based on income history alone.

    We went to a private lender. Mike had $280K in savings (a mix of RRSPs, TFSA, and cash), and he was buying a $750K home. His equity position was strong. The private lender approved him at 12.5% with a 1-year term.

    Was the rate painful? Absolutely. But Mike understood the game plan: make 12 months of on-time payments, file his first full year of T1 Generals showing decent income, and then refinance into an A-lender. When we refinanced him in early 2027, he got a 5-year fixed at 5.19%. The private mortgage cost him maybe $15K extra in interest — worth every penny to get into the house he wanted when he wanted.

    Step-by-Step: How We Actually Get It Done

    Step 1: Discovery Call (15 Minutes)

    We start with a quick phone call or meeting at our Surrey office. I need to understand your situation — how long you’ve been self-employed, what kind of business, what your rough income is, what you’re looking to do (purchase, refinance, renewal), and how much you have for a down payment or equity.

    Bring questions. I’ll answer them honestly, including whether you even need me. Some situations are straightforward enough that your bank will handle it fine.

    Step 2: Document Gathering

    Based on our call, I’ll send you a specific list of what I need. Usually it’s the documents I listed above — T1s, NOAs, incorporation docs, bank statements. If you use an accountant, they can send most of this directly to us.

    This is the step where most people drag their feet. I get it — nobody likes digging through tax returns. But having your documents ready on day one is the single biggest thing you can do to speed up your approval.

    Step 3: Analysis and Lender Selection

    This is where the broker’s value really kicks in. I’ll look at your full picture — income, credit, property type, down payment, timeline — and figure out which lender is going to give you the best combination of rate and approval likelihood.

    Sometimes that’s a bank. Sometimes it’s a B-lender. Sometimes we need to get creative. I’ve got relationships with dozens of lenders across the spectrum, and I know their underwriting quirks. Lender A might decline you while Lender B approves the exact same file — the difference is in knowing which one to approach first.

    Step 4: Submission and Approval

    Once we’ve picked the right lender, we package your application and submit it. For B-lenders and private lenders, approvals can come back in 1-3 business days. A-lenders take 3-5 business days. Some complex files take longer, but I keep you updated throughout.

    If there are conditions (and there almost always are), I’ll work with you to fulfill them — additional documents, explanations for credit inquiries, clarification on a write-off, whatever the underwriter needs.

    Step 5: Closing

    Once you have a firm approval, the file goes to your lawyer or notary for closing. In BC, this usually happens within 1-2 weeks of receiving final lender approval. I coordinate with your legal team to make sure everything moves smoothly.

    Common Mistakes Self-Employed Borrowers Make

    After two decades of doing this, I’ve seen the same mistakes repeated over and over. Here are the ones that cost people the most:

    Mistake 1: Waiting Until You’re House Shopping to Talk to a Broker

    I can’t count how many times someone calls me from a car outside an open house, pre-approval in hand from their bank, only to find out the bank used their T4 income from two jobs ago and their self-employed income wasn’t factored in at all. Talk to a broker before you start looking. We’ll tell you exactly what you qualify for, and we’ll make sure the pre-approval is actually worth the paper it’s printed on.

    Mistake 2: Being Too Aggressive with Write-Offs

    Look, I understand. You want to minimize your tax bill. But there’s a point where your write-offs make you look penniless on paper, and no lender will touch you except at private rates. If you’re planning to buy a house or refinance within the next 2 years, have a conversation with your accountant about your mortgage strategy. Sometimes paying a few thousand more in taxes translates to saving tens of thousands in mortgage interest.

    Mistake 3: Not Having Your Taxes Filed on Time

    This sounds basic, but it comes up constantly. If you’re self-employed, your personal tax return is due June 15th (with payment due April 30th if you owe). Lenders need to see filed returns. Unfiled returns = no mortgage. It’s that simple.

    Mistake 4: Changing Corporate Structures Before Applying

    Some people incorporate (or switch from incorporation to sole proprietorship) right before applying for a mortgage, thinking it’ll help. It usually does the opposite. Lenders want to see a stable business structure. If you’re thinking about restructuring, talk to me first. We’ll time it right.

    Mistake 5: Assuming Your Bank Is Your Only Option

    Your bank is one lender. I have access to 40+. The self-employed mortgage market in Canada has grown enormously in the past decade, and the products available through the broker channel are far better than what most people realize. You’re not stuck with whatever your bank branch offers.

    Understanding Your Rates: What’s Fair in 2026

    Rate awareness matters. Here’s a quick snapshot of what self-employed borrowers in BC are looking at right now:

    Mortgage Type Rate Range (5-Year Fixed) When to Use
    A-Lender (Conventional) 4.89% – 5.49% Strong T1 income, good credit, 20%+ down
    B-Lender (Stated Income / BFS) 6.49% – 7.99% Low declared income, 20%+ down, decent credit
    Private Lender 9.99% – 14.99% Short-term solution, 25-35% equity needed

    These rates fluctuate. By the time you read this, they may have shifted up or down by a quarter point. But the relative spread between these tiers stays roughly the same. A-lenders are cheapest, private is most expensive, B-lenders sit in the middle.

    Want to see what today’s rates look like for your specific situation? Check out our residential mortgage page for current rate specials, or reach out directly and I’ll pull live pricing for you.

    Equity Lending: When Income Doesn’t Matter

    There’s another path that many self-employed borrowers don’t know about: equity-based lending. These are private mortgages where the qualifying is done almost entirely on the value of the property and your equity stake, not on your income.

    If you own a property in the Lower Mainland that’s gone up in value significantly, you might have more equity than you realize. A home equity loan or second mortgage can give you access to that capital without needing to prove income at all. I’ve used this strategy for self-employed clients who need cash for business expansion, debt consolidation, or even to buy another property.

    MLI Select: A Lesser-Known Option

    Canada Mortgage and Housing Corporation (CMHC) offers a program called MLI Select that some self-employed borrowers can qualify for. It’s designed for affordable housing and includes provisions for non-traditional income verification. The rates are competitive — often close to A-lender pricing — and it can be a great fit if your income is modest but consistent, and you’re buying in a qualifying area.

    Not every deal fits MLI Select, and the approval process has its own quirks. But it’s worth exploring, especially if you’re a first-time homebuyer who happens to be self-employed. I’ve placed several clients into MLI Select deals and they’ve been very happy with the results.

    Why Work With a Mortgage Broker as a Self-Employed Borrower

    I’ll keep this brief because I know you’re busy. Here’s the value I bring to a self-employed borrower:

    • Access to 40+ lenders — not just the one your bank branch is pushing
    • Knowledge of stated income and BFS programs — most bank reps don’t even know these exist
    • Relationships with B-lenders and private lenders — I know their appetites, their quirks, their current turn times
    • I work on your timeline, not the bank’s — evening appointments, weekend calls, whatever works
    • My fee is paid by the lender — in most cases, you pay nothing extra for using a broker on a standard residential deal

    If you’re self-employed in Surrey, Vancouver, Langley, Abbotsford, or anywhere else in BC and you need a mortgage, the fastest path to a yes starts with a conversation.

    Frequently Asked Questions

    Can I get a mortgage if I’ve been self-employed for less than 2 years?

    It’s harder, but not impossible. A-lenders typically want 2 years of self-employment history. B-lenders are more flexible — some will accept 18 months with strong documentation. Private lenders are the most flexible and will often lend with just 6-12 months of business history if your equity position is strong enough.

    Do I need 20% down if I’m self-employed?

    For a conventional A-lender approval with standard income verification, you can put down as little as 5% just like anyone else — as long as your qualifying income supports it. But for stated income and BFS programs, most lenders require a minimum of 10-20% down. Private lenders generally want 25-35% equity.

    What’s the minimum credit score for a self-employed mortgage?

    A-lenders want to see 650+. B-lenders usually need 600+. Private lenders will look at files below 600 if the deal is strong on equity. I’ve seen approvals with credit scores in the mid-500s on private files.

    Can I use my corporation’s income instead of my personal income?

    Some BFS programs allow this — they look at the corporation’s retained earnings and revenue. But generally, lenders want to see personal income because that’s what you’ll use to make mortgage payments. If most of your money stays in the corporation, we need to structure the application carefully.

    Will a stated income mortgage show up differently on my credit report?

    No. A stated income mortgage from a B-lender appears on your credit report the same way a bank mortgage does — it’s a standard mortgage. Future lenders won’t know or care that you used a stated income program to qualify.

    How long does the whole process take?

    From first call to closing, budget 2-4 weeks for a typical self-employed mortgage through a B-lender. A-lenders are similar. Private lenders can close in as little as 7-10 days if all documents are ready.

    Can I switch from a private mortgage to a bank mortgage later?

    Absolutely. That’s the whole strategy. Use the private mortgage as a bridge — get your financial house in order, build your income history, and then refinance into a lower-rate product as soon as you qualify. I’ve done this for dozens of clients.

    What if I have CRA debt?

    It’s not a deal-killer, but it complicates things. Some lenders won’t work with you if you have outstanding CRA debt. Others will, especially if you’re on a payment plan. Be upfront about it — I’d rather know on day one than find out during underwriting.

    Ready to Get Started?

    If you’re self-employed in BC and you need a mortgage — whether it’s a purchase, a refinance, a renewal, or you just want to know what you qualify for — I’m here to help. You can reach me at 604-593-1550 or varun@kraftmortgages.ca, or use our online application to get the ball rolling.

    My office is in Surrey, but I work with self-employed clients across BC — Vancouver, Burnaby, Richmond, Langley, Abbotsford, Kelowna, Victoria, everywhere. Most of our communication is by phone and email, so location isn’t really a barrier.

    Don’t let being self-employed stop you from owning a home. There’s a path for almost every situation. Let’s find yours.

    Varun Chaudhry is a Licensed Mortgage Broker with the BC Financial Services Authority (BCFSA #M08001935) and President of Kraft Mortgages Canada Inc. He has been helping self-employed borrowers in BC get mortgages for over 23 years.

  • Mortgages for Tech Workers in Canada: The Complete Guide (2026)

    Mortgages for Tech Workers in Canada: The Complete Guide (2026)

    Tech worker reviewing mortgage options on laptop in modern Vancouver condo

    Mortgages for Tech Workers in Canada: The Complete Guide (2026)

    You earn a six-figure salary at a US tech company. You live in Vancouver, work remotely, and have solid savings. So getting a mortgage should be easy, right?

    Not always. In my 23 years as a licensed mortgage broker, I’ve seen highly paid software engineers, DevOps leads, and startup founders get turned down by their own bank — not because they can’t afford the payments, but because their income structure doesn’t fit the standard mortgage application.

    If you earn in US dollars, work as a contractor, receive compensation through RSUs, or have limited Canadian credit history, this guide is for you. Here’s how to navigate the mortgage process as a tech worker in Canada in 2026.

    Why Tech Workers Struggle with Traditional Mortgages

    Canadian mortgage underwriting was built around a simple model: a full-time employee with a T4, Canadian pay stubs, a Canadian credit score, and two years of stable income at the same employer. Deviate from that template, and things get complicated quickly.

    Tech workers routinely run into several of these issues simultaneously:

    • US-dollar income. You’re paid by an American company, which introduces currency risk in the lender’s eyes.
    • Contractor or 1099 status. Many tech professionals work as independent contractors rather than salaried employees.
    • No Canadian credit history. If you moved from the US or elsewhere, Equifax Canada may have a thin or empty file.
    • Variable compensation. RSUs, stock options, and performance bonuses make up a large portion of total earnings but don’t always count toward qualifying income.
    • New to the employer or country. Lenders like employment stability, and tech workers tend to move companies frequently.

    The good news? None of these are deal-breakers. You just need to know which lenders handle them and how to present your income properly.

    Pro Tip: Don’t apply at your bank branch first if you have non-traditional income. Banks follow rigid internal guidelines. A mortgage broker has access to 40+ lenders, including several that specialize in tech-worker income structures.

    The 4 Income Structures Tech Workers Have

    Not all tech income is treated the same by Canadian lenders. Understanding your category is the first step toward a successful application.

    1. Full-Time Remote Employee (T4 or US W-2 Equivalent)

    You work full-time for a US or Canadian tech company and receive a regular salary. If you’re on a Canadian payroll with proper T4s and pay stubs, you’re in the strongest position — most lenders will treat this as standard employment income.

    If you’re paid on a US payroll and remain a US employee working remotely from Canada, the process is slightly more involved. You’ll need to demonstrate income stability, and lenders will convert your USD income to CAD for qualifying purposes (more on that below).

    2. Contractor / Consultant (Self-Employed)

    You invoice through your own corporation or as a sole proprietor. This is common for senior engineers, architects, and specialized consultants who contract with one or more tech companies.

    Lenders treat you as self-employed, which means a two-year income history requirement and additional documentation. However, your actual income is often higher than what a salaried role would pay — the challenge is proving it to the lender’s satisfaction.

    3. Startup Founder / RSU-Heavy Compensation

    Your total compensation includes significant equity components — RSUs, stock options, or performance shares. Your base salary might look modest on paper, but your actual earnings are much higher once vesting events occur.

    Lenders vary widely on how much of this variable income they’ll use. Some will count 100% of vested RSU income averaged over two years, while others will only use 50% or exclude it entirely.

    4. Mixed Income

    You have a combination of the above — perhaps a base salary from a Canadian employer plus US-dollar consulting income, or a full-time role supplemented by contract work and RSUs.

    This is the most complex category, but also common. The key is organizing documentation for each income stream separately and working with a broker who understands how to combine them for qualifying purposes.

    How Canadian Lenders View US-Dollar Income

    Earning in USD while living in Canada is increasingly common, especially in the Vancouver-Seattle corridor. But it raises a legitimate question for lenders: what happens if the exchange rate shifts and your mortgage payments, which are in CAD, become harder to cover?

    Here’s how lenders handle it in practice:

    • Income conversion. Most lenders convert your USD income to CAD using the current exchange rate at the time of application. Some apply a discount (typically 80-90% of the converted amount) to account for currency fluctuation risk.
    • Documentation. You’ll need US tax returns (IRS 1040), W-2 forms, recent pay stubs, and an employment letter. If paid through a Canadian corporation, you’ll also need corporate financials and your T1 personal tax return.
    • Account verification. Lenders want to see the income actually arriving in a Canadian bank account. Prepare 3-6 months of bank statements showing regular deposits.
    • Tax obligations. If you’re a Canadian tax resident earning US income, lenders will want to understand your Canadian tax obligations. The after-tax income is what counts for qualifying.

    Key Insight: The exchange rate discount lenders apply can reduce your qualifying income by 10-20%. If you earn USD $150,000, a 90% conversion at a 1.35 rate gives you CAD $182,250 for qualifying — not CAD $202,500. This matters when you’re close to the threshold for the purchase price you want.

    Self-Employed Tech Workers: The Path to Approval

    If you’re incorporated or operate as a sole proprietor, here’s what to expect.

    The Two-Year Rule

    Most lenders require a minimum of two years of self-employment history. Some alternative lenders will accept one year, but you’ll typically pay a slightly higher rate or face a lower loan-to-value limit (80% instead of 95%).

    How Lenders Calculate Self-Employed Income

    For incorporated professionals, lenders generally use one of these methods:

    • Line 150 (net income) from your personal T1 tax return. This is the most conservative approach and the most common with major banks.
    • Corporate net income + your salary/dividends. Some lenders will add back certain business expenses, but this varies.
    • Stated income programs. A few lenders offer stated-income programs for self-employed borrowers where you declare your income and it’s reasonable for your industry, without requiring full tax return verification. These typically require 35% equity (65% LTV maximum).

    For sole proprietors, the calculation is based on your T1 General, specifically the net business income after expenses. The CRA Notice of Assessment (NOA) confirms the filed amounts.

    Documentation Checklist

    • 2 years of personal T1 tax returns with NOAs
    • 2 years of financial statements (if incorporated)
    • GST/HST returns (if registered)
    • Articles of incorporation
    • Business bank statements (12-24 months)
    • Contract agreements with your tech clients
    • HST/GST account statement from CRA

    Pro Tip: If you’re incorporated, keep your corporate and personal finances clean and separate. Comingling personal expenses through the corporation is the number one reason tech contractors see lower qualifying income on their T1.

    Foreign Credit History: What If You Have No Canadian Credit Score?

    Moving from the US to Canada for a tech job? You might have an 800+ credit score south of the border and a blank file at Equifax Canada. That’s frustrating, but it’s a solvable problem.

    Strategies to Build Canadian Credit Fast

    • Get a secured credit card immediately. TD, RBC, and other major banks offer secured cards with a deposit as low as $500. Use it monthly and pay it in full.
    • Ask your US bank about Canadian credit file sharing. Some US financial institutions can provide Canadian credit bureaus with payment history data.
    • Get added as an authorized user on a spouse’s or family member’s Canadian credit card. Their positive history helps build yours.
    • Pay rent through a rent-reporting service. Services like Borrowell’s RentBoost report your rent payments to Equifax Canada.

    Qualifying with Limited Canadian Credit

    If you don’t have two years of Canadian credit history, you still have options:

    • Alternative lenders often accept non-traditional credit documentation, such as 12 months of on-time rent payments, utility bills, and cell phone payments.
    • Newcomer programs from select lenders are designed specifically for new-to-Canada borrowers with strong foreign income and credit. These programs may accept US credit reports and foreign income documentation.
    • Equifax Canada’s newcomer initiatives can help establish a Canadian credit file using data from your home country where available.

    Key Insight: Start building Canadian credit the moment you arrive. A secured card used responsibly for 6-12 months, combined with rent reporting, can give you enough of a credit file for many lenders to work with.

    RSUs, Stock Options, and Bonus Income

    Tech compensation often includes equity — and that equity can represent a significant portion of your actual earnings. Here’s how lenders treat it.

    RSUs (Restricted Stock Units)

    RSUs are the most common form of equity compensation at major tech companies like Amazon, Microsoft, Google, and Meta. For mortgage qualifying purposes:

    • Vested RSUs that have been sold and deposited into your bank account are the easiest to use. Most lenders will average your vested RSU income over 2 years.
    • Upcoming vesting schedules can sometimes be considered by specialized lenders, but this is less common.
    • Usage rate varies: Major banks typically use 50% of average RSU income. Some monoline lenders will use 100% if you have a consistent 2-year vesting history.

    Stock Options

    Stock options (ISOs or NSOs) are harder to use because they represent potential future value rather than current income. Most lenders won’t count unexercised stock options. If you exercise options regularly and the income shows up on your tax returns, some lenders will consider it.

    Performance Bonuses

    Annual or quarterly bonuses are common in tech. Lenders typically average bonus income over 2 years and apply the same 50-100% usage rate as RSUs. If your bonus is guaranteed (written into your employment contract), some lenders will use 100% from year one.

    Required Documentation

    • RSU grant letters and vesting schedules
    • Brokerage statements showing vesting history and sales
    • T1 tax returns showing the income was reported
    • Employment letter confirming bonus/RSU structure
    • Recent pay stubs (if RSUs appear on pay stubs)

    Pro Tip: If RSUs make up more than 30% of your total compensation, you need a broker who works with lenders that count 100% of vested equity income. That single decision can be the difference between qualifying for a $800,000 home and a $1.1M one.

    Why Tech Workers Choose Kraft Mortgages

    The Vancouver-Seattle tech corridor is one of North America’s fastest-growing regions for remote tech talent. I’ve spent 23 years as a licensed mortgage broker in British Columbia, and I’ve built specific expertise in helping tech professionals navigate the mortgage process.

    What makes Kraft Mortgages different for tech workers:

    • Access to lenders who understand tech income. Not all lenders do. I work with a network that includes several who have dedicated programs for US-dollar earners, contractors, and RSU-heavy compensation.
    • Multi-stream income structuring. If you have a base salary, consulting income, and RSUs, I know how to present each stream to maximize your qualifying power.
    • Newcomer expertise. I work regularly with tech professionals relocating from the US, India, and elsewhere — including work permit holders and new permanent residents.
    • No wasted applications. Every lender submission is strategic. I won’t send your file to a lender that will decline it based on your income structure.

    Whether you’re buying your first home in Vancouver, refinancing in Toronto, or purchasing an investment property while working remotely for a Bay Area company, I can help you get approved.

    Tech professionals reviewing mortgage documents in modern office

    Key Takeaways

    • Tech workers face unique mortgage challenges because their income doesn’t match the traditional T4 + Canadian credit model — but none of these are deal-breakers.
    • US-dollar income is acceptable to most Canadian lenders, but expect a currency conversion and potential 10-20% discount on qualifying income.
    • Self-employed contractors need 2 years of income history and clean tax returns; incorporated status can help or hinder depending on how you structure your compensation.
    • RSUs and bonus income can count toward qualifying, but lender policies range from 50% to 100% usage — choosing the right lender matters enormously.
    • No Canadian credit score? Build it fast with a secured card, rent reporting, and authorized user status, or use newcomer programs that accept foreign credit history.
    • Work with a mortgage broker who specializes in tech-worker income structures — it saves time, avoids declines, and maximizes your purchasing power.

    Frequently Asked Questions

    Can I get a mortgage in Canada with US income?

    Yes. Many Canadian lenders accept US-dollar income for mortgage qualification. Your income is converted to CAD at the current exchange rate, and lenders may apply a 10-20% discount for currency risk. You’ll need US tax returns, W-2s, and proof that the income deposits into a Canadian bank account.

    What if I’m on a work permit?

    You can qualify for a mortgage on a work permit. Most lenders require your work permit to be valid for at least 1-2 years beyond the mortgage term. Some newcomer programs are specifically designed for work permit holders. A minimum down payment of 5-10% applies depending on the purchase price and lender.

    How do RSUs count toward mortgage qualification?

    RSU income that has vested and been sold can be used to qualify, averaged over 2 years. Major banks typically use 50% of average RSU income, while some monoline lenders will use 100% if you have a consistent vesting history. You’ll need grant letters, vesting schedules, brokerage statements, and tax returns.

    Can I qualify with no Canadian credit score?

    Yes, but you’ll need to use lenders that offer alternative credit programs. Options include newcomer programs, alternative lenders that accept rent and utility payment history, and secured credit card strategies to build a Canadian file quickly. If you have strong US credit, some lenders will review your US credit report.

    What if I’m a contractor instead of a full-time employee?

    Contractors are treated as self-employed borrowers. You’ll need a 2-year history of contract income, supported by tax returns, contracts, and bank statements. If you’re incorporated, your qualifying income is based on your personal T1 net income or corporate income (depending on the lender). Some lenders offer stated-income programs with 35% down.

    What’s the minimum down payment for a tech worker?

    The same rules apply as any other borrower: 5% on the first $500,000, 10% on the portion between $500,000 and $1,000,000, and 20% on amounts above $1M. For properties over $1.5M, you’ll need at least 20% down. If you’re self-employed with less than 2 years of history or have no Canadian credit, some lenders may require 20-35% down.

    Do I need a 2-year employment history?

    For standard qualification, most lenders want 2 years of employment or self-employment history. However, if you’re newly moved from the US but worked in the same role or industry, many lenders will count your foreign employment history. If you’ve been in your current role for less than 2 years but have strong income and credit, some lenders are flexible.

    What documents do I need to apply?

    It depends on your income structure, but generally: government-issued ID, 2 years of tax returns (Canadian T1 and/or US 1040), recent pay stubs or contract agreements, NOAs, bank statements (3-6 months), RSU/bonus documentation if applicable, and an employment letter. Your broker will give you a specific list based on your situation.

    Can I get pre-approved before finding a property?

    Absolutely. In fact, I recommend it. A pre-approval gives you a firm rate hold (typically 90-120 days) and shows sellers you’re a serious buyer. For tech workers with complex income, the pre-approval process also identifies any documentation gaps early — so there are no surprises when you find the right home.

    Ready to Get Started?

    Getting a mortgage as a tech worker doesn’t have to be complicated — but it does require working with someone who understands your income structure. Whether you’re paid in USD, working as a contractor, or building your Canadian credit from scratch, I can help.

    Apply now and let’s find the right mortgage for your situation.

    Contact Kraft Mortgages →

    Apply through Finmo →

    Varun Chaudhry is a Licensed Mortgage Broker with the BCFSA (#M08001935) and President of Kraft Mortgages Canada Inc. with over 23 years of experience helping Canadian homeowners and tech professionals secure mortgage financing.